College finances 101: How to help your high school senior pay for college

2026-11-10T06:01:00

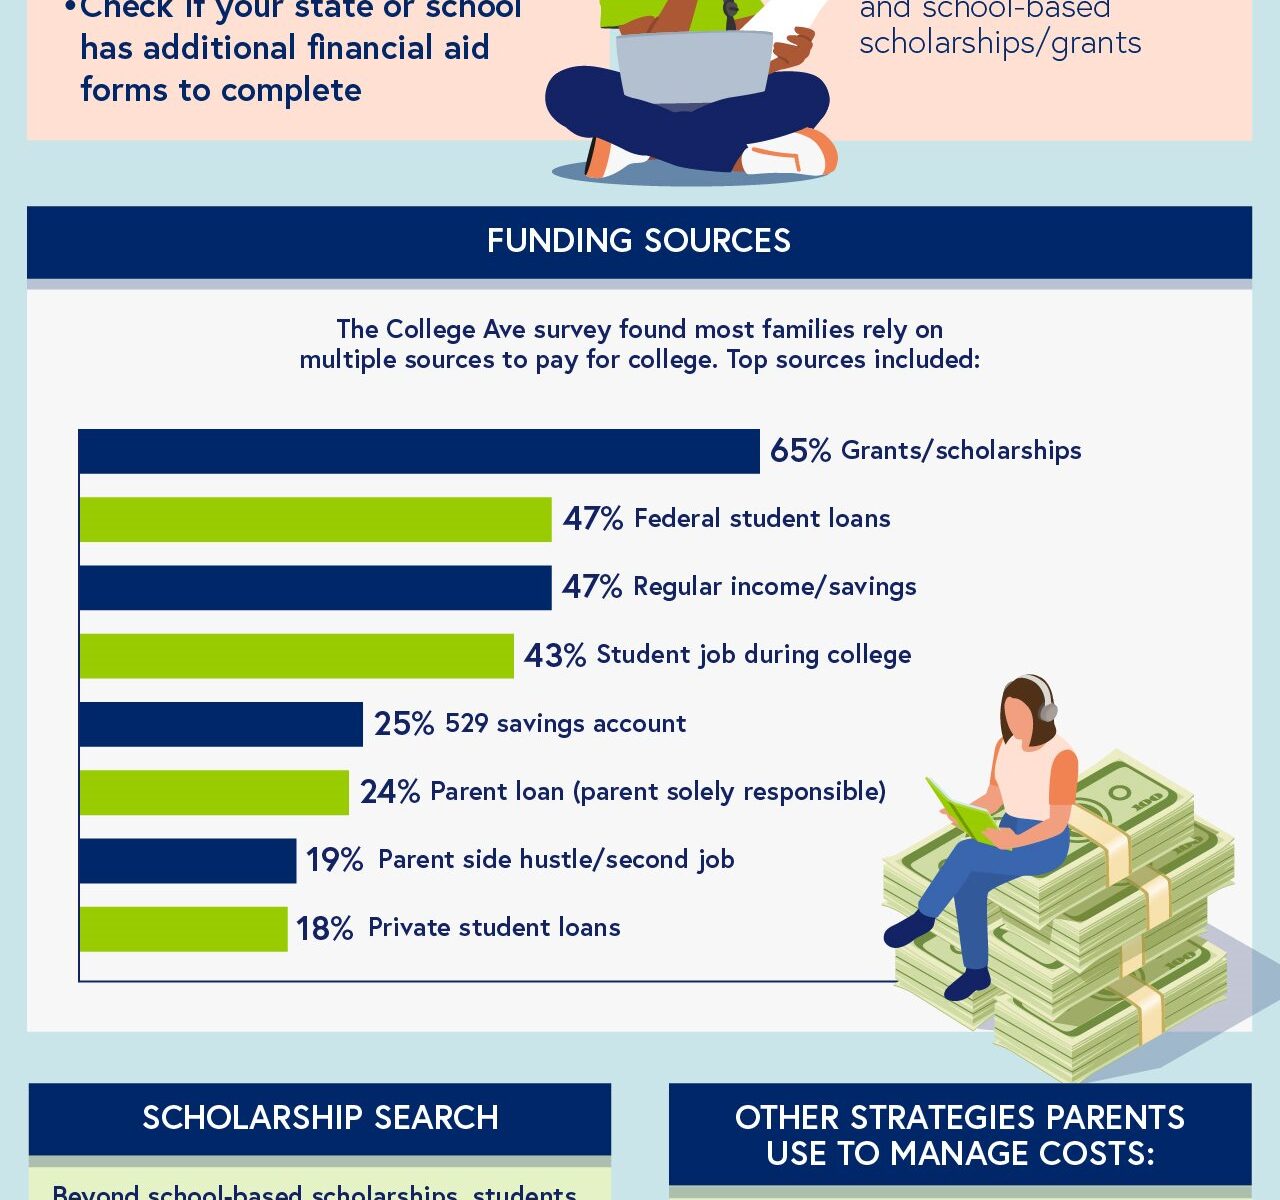
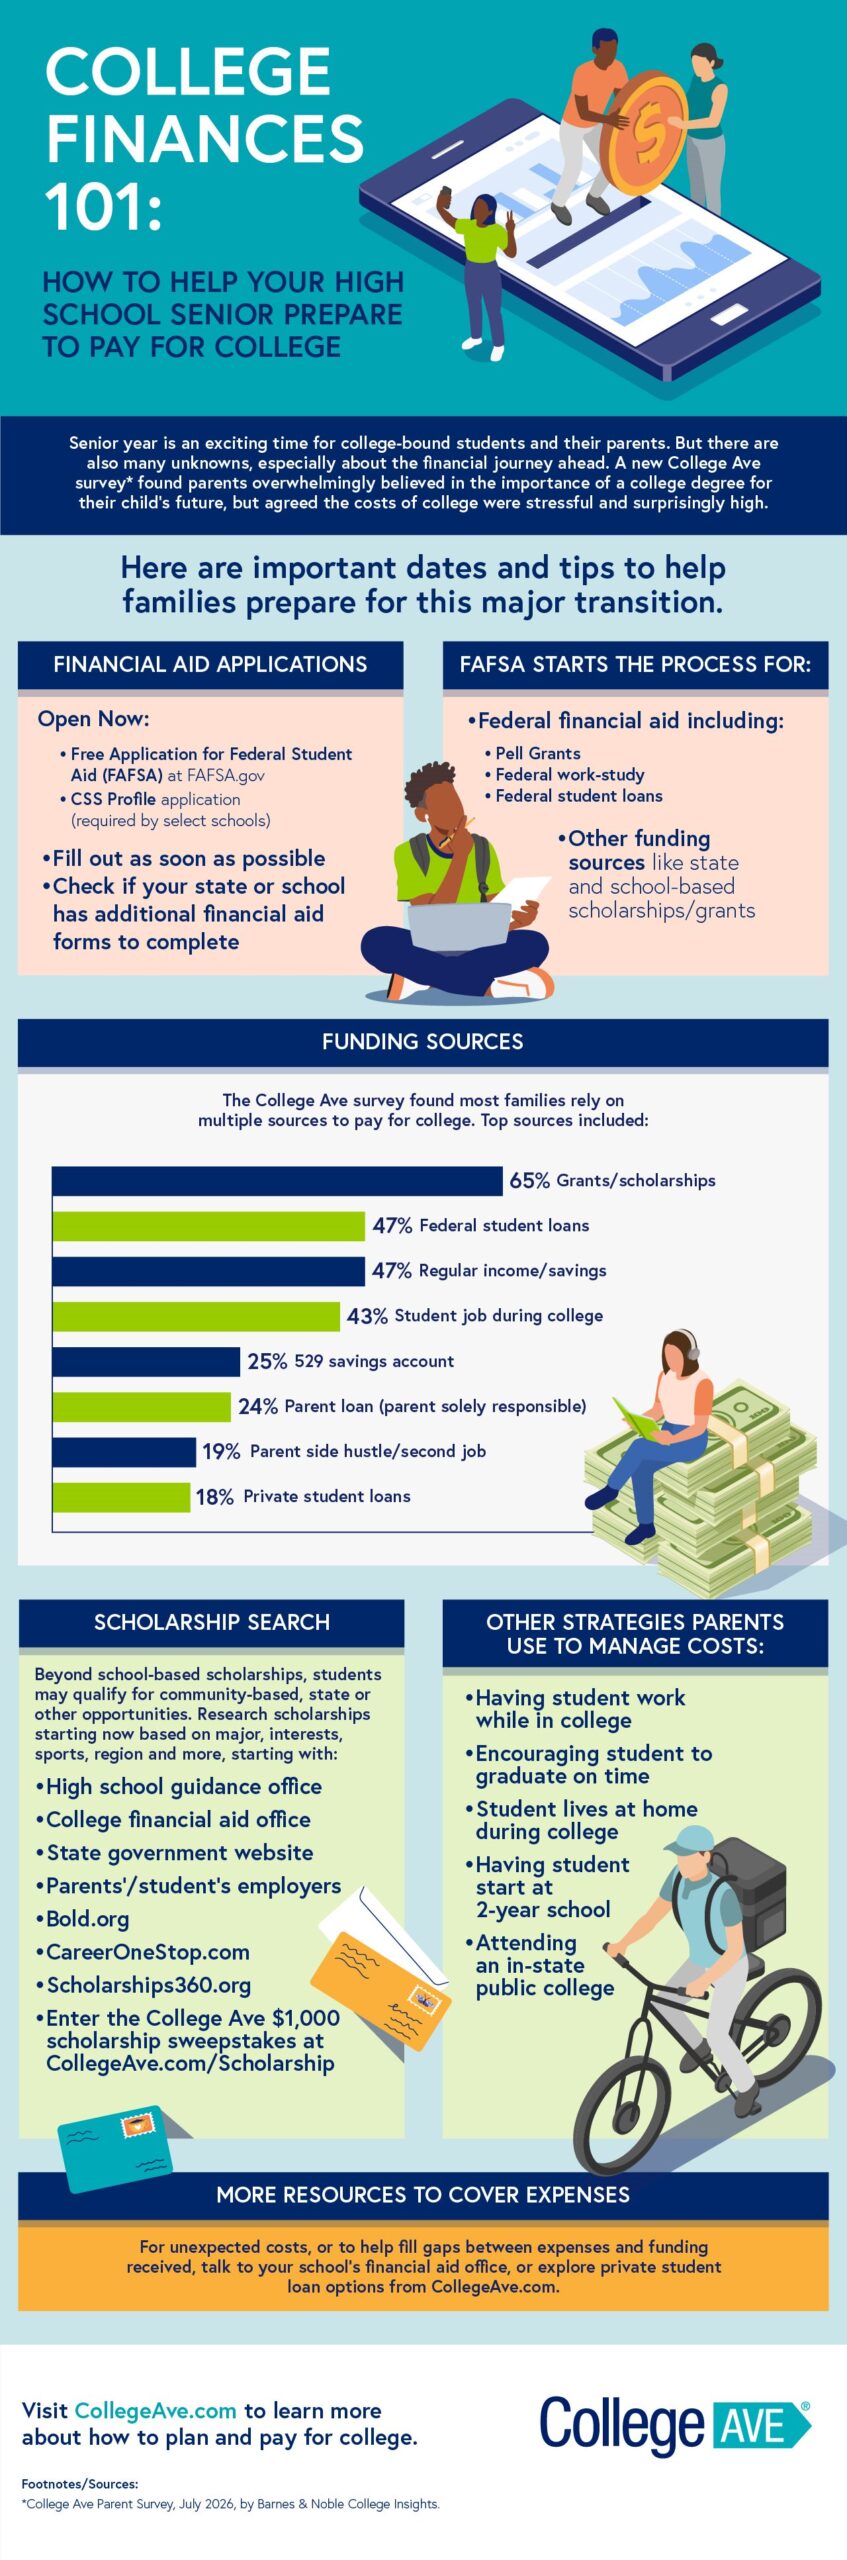
(BPT) – Senior year is an exciting time for college-bound students and their parents. But there are also many unknowns, especially about the financial journey ahead. A new College Ave survey* found parents overwhelmingly believed in the importance of a college degree for their child’s future, but agreed the costs of college were stressful and surprisingly high. Here are important dates and tips to help families prepare for this major transition.

Infographic

How to help prepare for your child’s unpredictable future

2026-11-09T08:01:00

(BPT) – Your children’s career opportunities and education pathways may look very different from the ones you knew. Learn about practical steps that can help families keep more possibilities within reach.

Key takeaways

  • Families can begin preparing for a child’s future career without knowing what that career will look like.
  • A flexible approach can support a range of education and training pathways.
  • Small, consistent steps can help keep future choices more attainable.

Have you ever asked a young child what they want to be when they grow up? The answer may change by the week. Even when students are older, they are constantly exploring a rapidly evolving mix of careers, credentials and training options. For parents, that uncertainty makes planning feel intimidating. How can you prepare when you cannot know whether your child will choose a university, a technical program, an apprenticeship or a career that doesn’t even exist yet?

The good news is that families do not need a perfect prediction. They need a practical plan that can grow and adapt along with their child. These five steps can help parents focus less on choosing a path today and more on creating options for tomorrow.

1. Keep possibilities open

Instead of building a plan around a single school or career, think broadly about the kinds of learning your child may need after high school. That could include a two-year or four-year degree, career and technical education, industry credentials or another eligible training program. A broader mindset can reduce the pressure to have every detail figured out now.

2. Create a savings habit early

Future education costs can feel overwhelming when viewed as one large number. A more approachable strategy is to contribute into a savings vehicle like an Investment 529 Plan that fits your current budget, and make it consistent. Consider automating deposits after payday, redirecting part of a tax refund or adding a portion of a raise. The amount can change as your circumstances change. The habit creates momentum. The elementary school years are an especially valuable time to begin because families often have more years to save, allowing small contributions to accumulate over time.

We didn’t start with a large amount. We just started with what we could afford and made it part of our routine. For me, the biggest lesson was that you don’t have to be perfect. You just have to start.

3. Make it easy for family and friends to help

Dad and daughter, with her backpack, hugging. Florida Prepaid is the most successful prepaid plan in the nation.

Birthdays, holidays and milestones often bring more toys and gifts than a child needs. Let grandparents, relatives and close friends know that contributing toward future education is another meaningful option. Even occasional gifts can complement what parents are already saving and help loved ones feel connected to a child’s long-term goals.

4. Review your plan annually

Choose a yearly reminder date like your child’s birthday or new school year to review your progress. Ask whether the contribution still fits your budget, update family information and consider whether your goals have changed. Yearly check-ins can help keep the plan current.

5. Choose flexible tools

When comparing education savings options, look beyond the name of the account. Ask where the funds may be used, what expenses qualify, whether the beneficiary can be changed and what happens if plans shift. Understanding those choices helps families select an approach that supports multiple routes after high school.

For Miami parent Ann Fonts, opening an education savings account wasn’t about having all the answers. It was about getting started. “Like a lot of parents, I thought I had more time,” Fonts said. “Then one day I was registering my son for kindergarten and wondering where the years had gone. We didn’t start with a large amount. We just started with what we could afford and made it part of our routine. For me, the biggest lesson was that you don’t have to be perfect. You just have to start.”

As children grow, their interests and ambitions will change. A flexible plan gives families room to respond without waiting for certainty before they begin.

The most important first step is not choosing the perfect path or saving the perfect amount. It is starting with what is realistic, building a routine and revisiting the plan over time. Those actions can help turn an unpredictable future into one filled with more opportunity. Whether today’s dream is becoming a teacher, welder, nurse, entrepreneur, engineer or a career that hasn’t been invented yet, parents don’t need to know exactly where their child is headed to help them prepare. Taking manageable steps today helps keep more opportunities within reach tomorrow.

Explore education savings options and build a plan around your family’s goals and budget at MyFloridaPrepaid.com/plans/build-your-plan.

Beyond the classroom: How learning and AI fuel entrepreneurship

2026-11-04T08:01:01

(BPT) – Artificial intelligence is changing the rules of entrepreneurship, breaking down traditional barriers and opening new doors for aspiring business owners. This National Entrepreneurship Month, DeVry University is showcasing students and alumni who are capitalizing on these opportunities, supported by the university’s longstanding entrepreneurship programs, faculty-led initiatives, industry partnerships, and emphasis on AI and technology skills.

According to the U.S. Department of the Treasury, the United States averaged 430,000 new business applications per month in 2024. With AI accelerating the pace of innovation, entrepreneurs need both business knowledge and technical skills to stay competitive, a combination reflected in the experiences of DeVry students and alumni.

For Claudia Mirza, investor and CEO at Fluyenta/RunMyProcess, a global workflow automation company, the value of that education has extended well beyond graduation.

“I graduated back in 2002 with a bachelor’s in business administration,” she said. “Who would have imagined that more than two decades later, the education I received would continue to shape my career, open new doors and create opportunities for growth?”

Her 19-year-old son, Anwar Mirza, has inherited his mother’s entrepreneurial spirit. At 16, he co-founded NIXAR Solutions, a Frisco, Texas-based AI automation, coaching and marketing agency. Now pursuing an associate degree in cybersecurity and networking at DeVry, Anwar aims to strengthen his technical expertise and better understand the work of his company’s developers.

“I was previously studying finance at a traditional four-year university, but when I attended a tech conference in Austin with my mom, I realized that cybersecurity is the key to the current tech revolution,” he said. “After speaking with DeVry enrollment counselors about the cybersecurity courses available, I was excited about the opportunity to pursue this field.”

Both mother and son knew that a traditional university experience wasn’t right for their lives.

“I needed my education to be able to work with my work schedule,” Claudia said. “And now I see how having a flexible online education benefits my son. He travels with me, attends conferences, and just finished a training in Switzerland. DeVry’s flexible curriculum has allowed him to continue running his business and achieve his goals while pursuing an education that fits into his schedule.”

Equipping entrepreneurs for long-term success

DeVry University has been a starting point for many entrepreneurs and continues to expand its offerings to help current students and alumni build on their skills and pursue long-term success.

For instance, the university partnered with 1871 to launch a Graduate Certificate Program in Innovation and joined the Startup Roadmap Program, a 12-week program for entrepreneurs. So far, three cohorts of DeVry students and alumni have completed the program, gaining hands-on experience in launching and growing a business.

Mark Sloboda, a two-time DeVry graduate and founder of Blinner, experienced that firsthand. Through the Startup Roadmap Program, he strengthened his understanding of customer identification, product-market fit, and when to scale a business. Like Claudia, he credits his education with laying the foundation for his success.

“My DeVry education has been extremely important in my journey and my success in how I build and create,” said Sloboda. “That foundation helped me navigate the trial and error that comes with both technology and entrepreneurship.”

Another way the university helps aspiring entrepreneurs put their skills into practice is through the faculty-led Collegiate Entrepreneurship Initiative (CEI). For eight years, the annual CEI competition, led by Dr. Lilbert Ontai and Dr. Kimberly Bankston-Bradshaw, has helped students launch or grow their businesses through workshops and presentations.

The power of lifelong learning

As emerging technologies continue to transform industries, entrepreneurs face an ongoing challenge: keeping pace with change. For some graduates, one of the most valuable lessons from their education is knowing how to continue learning.

“It’s been 43 years since I graduated from DeVry with a Bachelor of Science in Electronics Engineering Technology,” said Milton Mattox, Ed.D., CEO of the United States Artificial Intelligence Institute (USAII). “How does a kid from Atlanta, Georgia, who went to DeVry in the ’80s become known for artificial intelligence, quantum computing, post-quantum cryptography and cybersecurity? You do it by knowing how to learn and keep learning. That’s what my time at DeVry taught me.”

That foundation of knowing how to learn and engaging in lifelong learning continues to impact current DeVry students.

“The discussions in my tech foundations class go beyond my time in the classroom,” Anwar added. “It sparks conversations that I continue to think on and discuss outside of coursework and the school environment.”

His mother agrees.

“Nearly 25 years later, I’m still benefiting from the fundamental skills I learned at DeVry,” Claudia added.

To learn more about DeVry’s entrepreneurial education offerings, visit DeVry.edu.

Getting Ready for Open Enrollment: Your Questions, Answered

2026-10-29T10:01:00

(BPT) – Have questions about this year’s open enrollment? From important dates to choosing a health plan, here’s what you need to know to prepare and enroll with confidence.

What is open enrollment?

Open enrollment is the time of year when you can sign up for health insurance, renew your existing plan or shop for a new one. If you miss this period, you may need to wait until next open enrollment to sign up, unless you have a qualifying life event, such as losing coverage, having a baby or getting married, which qualifies you for special enrollment.

When does open enrollment begin, and what dates should I know?

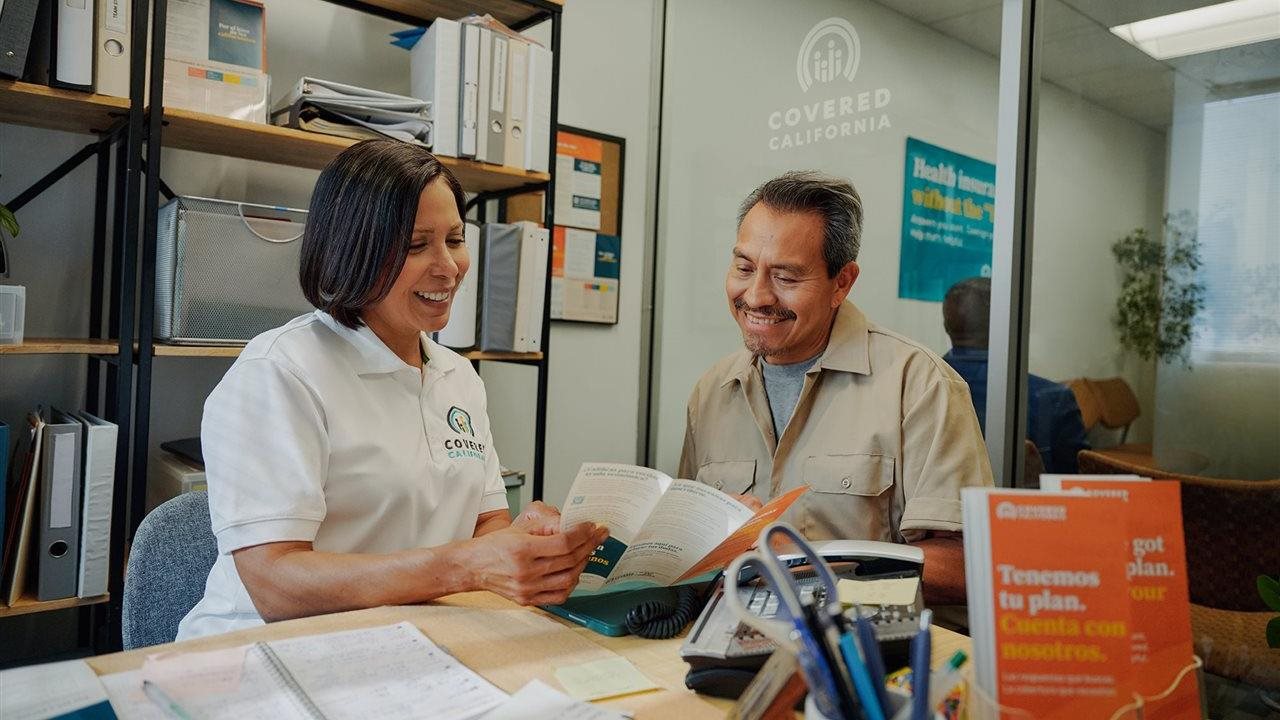
Open enrollment dates depend on where you get your health insurance. If you get coverage through your employer, your enrollment dates may be different. For those getting health coverage through Covered California — open enrollment begins Nov. 1 and ends Jan. 31. You can sign up online, by phone or in person.

If you enroll in November and December, your coverage begins on Jan. 1. If you enroll in January, your coverage begins Feb. 1.

What information should I gather before I apply or renew my coverage?

When you apply or renew coverage, you’ll need to have the following information ready:

  • Social Security numbers for everyone applying
  • Federal tax information
  • Immigration documents, if applicable (Green Card, I-94, EAD)
  • Employer information and estimated household income
  • The number of people in your household, including their ages and incomes

Having this information can make the process easier. You may not need to submit documents when you first apply. If anything else is needed to confirm your eligibility, Covered California will contact you with the specific documents to provide.

What should I consider when choosing a health plan?

Whether you’re getting health insurance for the first time or looking for a new plan, consider these questions:

  • Who needs coverage?
  • How often do you visit the doctor?
  • What health services do you expect to need?
  • Are your preferred doctors and hospitals included in the plan?
  • Are your prescription medications covered?
  • How much would you pay each month and when you get care?

Your answers can help you compare plans and find one that fits your health needs and budget.

What do terms such as premium, deductible and copay mean?

Health insurance comes with different types of costs. Here are a few common terms to know:

  • Premium: The amount you pay each month to have a health plan.
  • Deductible: The amount you pay for covered services before your plan starts paying its share — similar to car insurance where you might need to pay a deductible to cover part of a repair.
  • Copay (or copayment): A fixed amount you pay for a covered service, like a doctor visit or prescription.

Many insurance plans include both deductibles and copays. A general rule is that policies with higher premiums have lower deductibles and copays, while those with lower premiums have higher deductibles and copays. By offering a diversity of plan options, health insurance companies provide consumers the opportunity to choose a plan that best suits their needs.

Here are some other terms that are useful to know when enrolling:

  • Coinsurance: The percentage of the cost you pay for a covered service, after you meet your deductible.
  • Out-of-pocket costs: What you pay yourself for care. This includes deductibles, copays and coinsurance.
  • Out-of-pocket maximum: The most you’ll pay in a year for covered services. After that, your plan pays 100% of covered costs.

What does coverage include, and how do I know which level is right for me?

Every Covered California plan covers the same core set of health services — no matter its level or type:

  • Outpatient care (care without a hospital stay)
  • Emergency services
  • Hospital care, including surgery and overnight stays
  • Pregnancy, maternity and newborn care
  • Mental health and substance use services, including behavioral health treatment
  • Prescription drugs
  • Rehabilitation and habilitation services and devices
  • Lab services
  • Preventive care, wellness services and chronic disease management
  • Pediatric services, including children’s dental and vision care

Each plan has four levels of coverage: Bronze, Silver, Gold and Platinum. Plans cover the same core categories of health services, including doctor visits, emergency care, hospital stays, prescription drugs, mental health care and preventive services. The main difference is how you and your health plan share the costs.

For example, plans with higher monthly premiums generally have lower costs when you receive care. There’s no single right choice. Consider your budget, how often you expect to need care and the doctors or medications you want covered. You can learn more about Covered California’s coverage levels here, and use the Shop and Compare tool on CoveredCA.com to get an estimate based on your situation.

How can I find out if I qualify for financial help?

Covered California is the only place where you can receive financial help to lower the cost of your health insurance through state and federal tax credits. In fact, four out of five people who enroll through Covered California qualify for financial help.

Today, Californians can get more financial help than ever before. Learn about how this works through both premium tax credits to lower the cost of your monthly premium and cost-sharing reductions that save you money when you get care. You can get a quick estimate to find out how much financial help you might get here.

What should I know if my income or household has changed?

If your income or household has changed, update your Covered California account as soon as possible. For 2027 coverage, use your best estimate of the income you expect to earn in 2027, rather than what you earned last year. If your income is hard to predict, make your best estimate and report changes during the year. This helps make sure your financial help amount is as accurate as possible.

Where can I get free, confidential help with open enrollment?

Free, confidential help through Covered California is available by phone, online and in person. Certified enrollers can answer questions about plans, help you understand possible financial help and guide you through enrollment. Assistance is available in multiple languages.

  • By phone: Call 800-300-1506 to speak with a Covered California representative.
  • Help on demand: Request a free callback from a certified enroller for first-time applicants.
  • In-person help: Find a certified enroller or agent near you through CoveredCA.com.
  • Online: Visit CoveredCA.com for live chat and other help options.

Open enrollment begins Nov. 1. Start preparing now at CoveredCA.com.

Get your whole team fluent in generative AI

2026-10-27T15:01:04

(BPT) – Key takeaways

  • If only the leadership team has generative AI training, a bottleneck ensues, because the wasted hours live on the front line.
  • Free self-paced training courses from the AI companies are worth taking, and each one teaches a single platform.
  • AI products change month to month, so the timing of AI training matters as much as what it covers.
  • AI certification gives a client something visible to trust.

A recent survey by Certified AI 360 found 84% of respondents said their company is not ready for AI. In most of those companies the tools are already paid for. The skills are the line item nobody budgeted.

The AI skills gap describes a company’s paid tools and the employees who lack the skills to use them. It opens in a predictable way. An owner and a couple of managers try ChatGPT, CoPilot, Claude or another model, find it useful, and everyone else keeps working exactly as they did before.

Prioritize training the people doing the work

Most AI rollouts begin at the top, because that is where the budget sits. The bottleneck shows up a quarter later, when the only fluent people in the building are the ones furthest from customer calls and proposals.

Sam Richter is co-founder and lead instructor of Certified AI 360, a Hall of Fame professional speaker who has trained more than 1 million business professionals worldwide.

“When two managers are the only ones trained, every AI idea in the building waits in line behind their calendars,” said Richter. “The people writing the quotes and answering the phones know where the wasted hours are. Give them the skills and they will go find them.”

Are free AI courses enough to train a team?

Free AI training courses are a real starting point, and each one teaches a single platform. Anthropic opened Claude Academy with free courses on AI fluency and workplace rollout on Aug. 20, according to EdTech Innovation Hub. OpenAI Academy publishes free self-paced courses on applying AI at work, and every major AI company now offers instruction on its own product. Subscription libraries such as LinkedIn Learning add breadth, bill per person per month and run on pre-recorded video.

“What no business gets back is the customer who went with the competitor who answered faster and knew more.”

Sam Richter, co-founder and lead instructor of Certified AI 360

An employee who finishes one of those courses knows one tool well. On a normal Tuesday that same employee may open Copilot in Outlook, Gemini in a shared document and ChatGPT on a phone.

What to look for in AI team training

When considering team training options, prioritize these four factors:

  • Coverage of more than one platform, so people choose the right tool for the task at hand rather than the one the company happened to buy.
  • An update schedule you can see. A course recorded a year ago teaches habits the tools have already outgrown.
  • Lessons shaped like the job: a sales email that earns a reply, or a contract summarized before a Monday meeting.
  • Proof at the end that a customer can actually see.

Certified AI 360 is a whole-company AI training and certification program for small businesses, covering ChatGPT, Claude, Gemini, Copilot and every major AI platform. Training runs about 8 hours per employee. It’s self-paced, the curriculum is updated weekly, and every employee who finishes earns an individual credential while company plans also earn a company badge.

“Eight hours is less than one workday, and any business can find that,” said Richter. “What no business gets back is the customer who went with the competitor who answered faster and knew more.”

Take the free 10-question AI readiness assessment and see how whole-company certification works at www.certifiedai360.com.

What do economic development organizations actually do?

2026-10-27T08:01:00

(BPT) – Key takeaways:

  • Economic development organizations (EDOs) help fund small businesses, create new opportunities and revitalize public spaces in communities nationwide, but most people may not be familiar with the term.
  • EDOs like the Michigan Economic Development Corporation (MEDC) work to improve communities through investing in local businesses, attracting new business to the area and enhancing spaces like downtowns and parks.
  • Whether you’re an entrepreneur, a developer or simply a resident, you’ve likely already benefited from an economic development program in your community.

While some people haven’t heard the term “economic development organization” (also called an EDO), the results of these organizations show up everywhere. EDOs are making a positive impact in communities in many different ways, from new job postings to a vacant storefront transforming into a coffee shop to the park families visit every weekend.

What does an EDO do for your community?

EDOs commonly focus on areas such as enhancing public spaces, supporting the workforce through training, helping entrepreneurs and businesses create local jobs and recruiting new business investments in a specific area.

For example, the Michigan Economic Development Corporation (MEDC) is an EDO with a mission to support small businesses and entrepreneurs, attract businesses to the state, grow the workforce and develop attractive places, from downtowns to parks and more. These goals are accomplished through programs like small business grants, mentorships for entrepreneurs and public space revitalization projects.

The details may look different from state to state, but the mission remains the same: Somewhere in your own community, an EDO is working to help it thrive.

How do EDOs affect jobs, communities and small businesses near you?

There are numerous ways EDOs make a real-life impact in your area. Using the MEDC as an example, here are a few ways EDOs can benefit businesses and communities throughout a state:

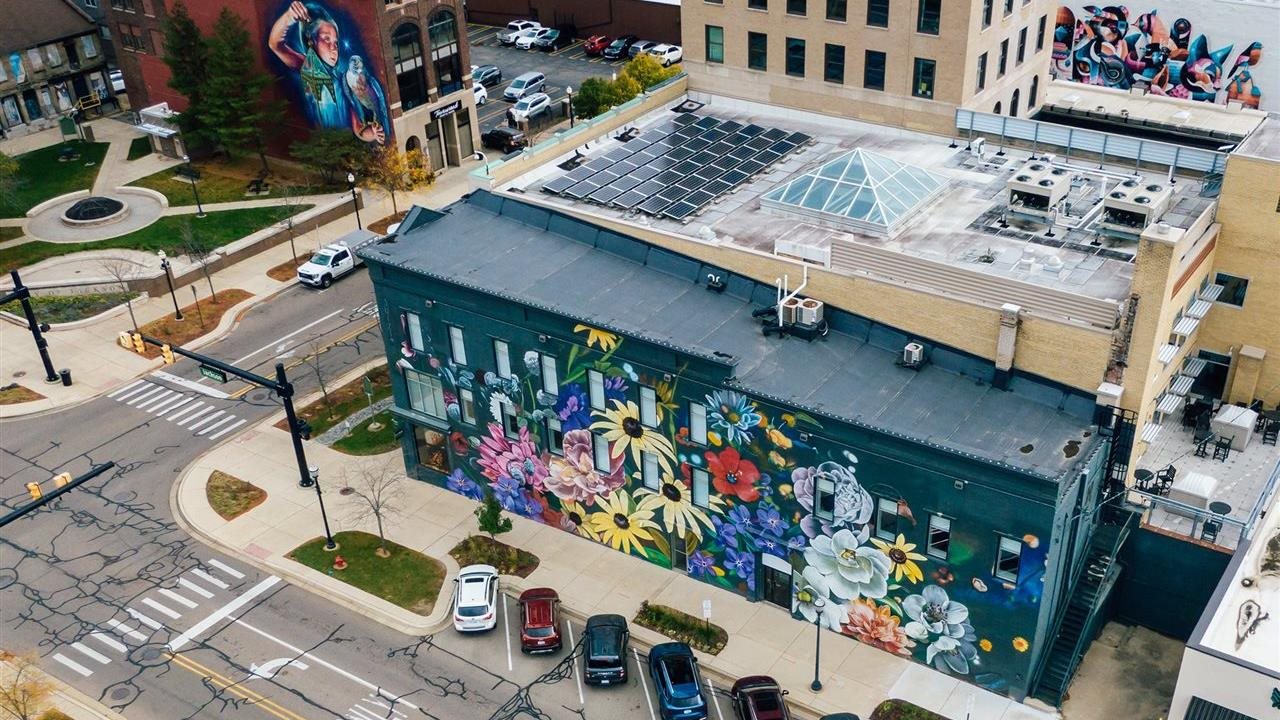
  • Beautifying downtowns like Howell, a participant in the MEDC’s Michigan Main Street Program. Communities engaged with this program are eligible for grants that support small businesses and placemaking projects in their districts. Howell transformed its downtown into a destination by attracting new and revitalized businesses, like Coratti’s Pizzeria Bar and Bocce, Frontal Lobe co-working space and the recently restored Howell Opera House. The businesses were complemented by new murals, art-inspired bike racks and an alley transformed into a pedestrian plaza and outdoor art gallery. These projects led to Howell receiving the prestigious Great American Main Street Award in 2018.
  • Providing small business support to help entrepreneurs transform ideas into thriving companies. For example, a business development grant helped West Michigan tech startup Ludus expand its digital ticketing platform and create new jobs. The MEDC also provides hands-on mentorship through Small Business Support Hubs like TechTown Detroit, which offers personalized resources to aspiring entrepreneurs. Groovy Donuts built a decade of bakery success with mentorship and grant support from the Lansing Economic Area Partnership’s TREK Small Business Support Hub.
  • Growing the entrepreneurial ecosystem to connect founders with the resources they need to scale. The MEDC provided a $1.5 million business incubator grant to support Flint’s 100K Ideas, a nonprofit organization helping local entrepreneurs launch and build their ideas through direct client services, workshop programming, pitch competitions, youth engagement and more. Additionally, a statewide competition created by the MEDC and the MSU Research Foundation, the PitchMI Startup Competition, connects promising Michigan founders with the capital, visibility, relationships and resources they need to move farther, faster.
  • Revitalizing buildings steeped in history breathes new life into old structures and adds critical housing to communities, with support from placemaking grants like those behind The Milton in downtown Battle Creek and the Walter French apartments in Lansing. Formerly known as the Heritage Tower and vacant for over a decade, The Milton project transformed a historic community building into a vibrant mixed-use development including apartment units and commercial space. In Lansing, the former Walter French Junior High School was converted into a mixed-use affordable housing and community hub.
  • Attracting major employers through incentives for business investments, site readiness and other initiatives that create a flourishing business climate. Thanks to the MEDC’s efforts, companies like LG Energy Solution and Torc Robotics have boosted job creation and investment across the state. LG Energy Solution opened its new Lansing battery plant in August 2026, and a recent report by the W.E. Upjohn Institute for Employment Research found the project will generate $2.53 in economic benefit for every $1 of state support. Torc Robotics, an independent subsidiary of Daimler Truck AG, chose to build its new engineering innovation center in Ann Arbor, bringing up to 500 new jobs to the region.

Through these and other programs, the MEDC continually works to support thriving communities throughout the state of Michigan, work that’s helped the state climb to No. 6 in CNBC’s Top States for Business rankings and land in Area Development’s Top 10 for three years in a row. The details may look different from state to state, but the mission remains the same: Somewhere in your own community, an EDO is working to help it thrive.

Frequently asked questions

  • What does “economic development” mean?
    Simply put, this means making investments in and creating programs for the improvement of a city, state or region. Economic development is often performed by government agencies such as the MEDC in Michigan, nonprofit organizations and private businesses, with goals like improving local infrastructure, enhancing public spaces and creating more opportunities for employers and employees.
  • What’s the difference between a chamber of commerce and an EDO?
    The two are often confused, but they serve different roles. A chamber of commerce is a membership organization that advocates for local businesses and is typically funded through member dues. An EDO like the MEDC focuses on economic growth for a specific city, state or region, often through grants, site development and partnerships with local organizations rather than membership. The two frequently work together, but an EDO is usually the one supporting programs like small business hubs or downtown revitalization.
  • Where can I find help for my business?
    Start with your local EDO for services like mentorship, training, technical assistance and networking opportunities. In Michigan, for example, the MEDC connects business owners with these resources, personalized guidance, funding opportunities and more: MichiganBusiness.org.

The fundamental homeownership guide for first-time buyers

2026-10-15T08:01:01

(BPT) – Sponsored by Chase Home Lending

Key takeaways:

  • First-time homebuyers can feel intimidated by the homebuying process. However, there are resources that can help them prepare to enter the housing market.
  • Chase Home Lending has created a guide of essential topics and tips that can help first-time buyers start their journey to homeownership with confidence.

If you’ve never bought a home before, the idea of starting the process can be frightening. The good news? You don’t have to do it alone.

To help you start your journey, Chase Home Lending offers this essential primer on the key aspects of homeownership that first-time buyers should know before entering the market.

Let a home lending professional be your guide

Before you begin searching for your home, consult a home lending professional. They can help you get preapproved, navigate the homebuying market and review loan options.

What are all the costs of homeownership

If you’re making the move from renting to owning, you may be focused on the opportunity to build home equity but perhaps overlook the added costs like property taxes and home maintenance. Taking the time to understand the full scope of homeownership can help you decide if the time is right to buy.

Explore educational resources

If you’re a first-time buyer, the homebuying process can seem overwhelming. However, there are many resources available to help boost your homebuying knowledge, such as how-to guides, webinars and podcasts.

Pro tip: Make sure to check the Chase Homebuyer Education Center, where you’ll find answers to mortgage questions, useful tips for buying and maintaining a home and an Affordability Calculator that can help you determine how much home you can afford.

Learn about the factors that determine the mortgage approval process

During the mortgage approval process, lenders carefully review several factors that determine if they’ll approve your mortgage and at what rate. Two important factors that influence their decision are your credit score and debt-to-income ratio.

Your debt-to-income ratio — how much of your gross monthly income goes toward monthly debt payments like rent, student and auto loans and credit card payments — helps creditors assess your financial health and creditworthiness. Lenders typically want to see that your DTI is low, as it tells them you’ll be able to manage your monthly payments with minimal issues.

Your credit score helps determine the interest rate and other costs you pay on a mortgage loan. If your credit score is high, it tells lenders that you have paid your bills on time and that you are responsible with your money, making you a more attractive candidate for a home loan.

null


Understand your options beyond conventional loans

Interest rates and fees can vary widely across lenders. Taking the time to compare options from banks, credit unions and online loan providers can help secure a better rate.

Don’t forget that loans come in all different shapes and sizes. Conventional loans aren’t your only option. There are programs like FHA* and VA** loans, plus other options like fixed-rate mortgages, adjustable-rate mortgages*** (ARMs) and low-down-payment loans that can provide greater flexibility and help with affordability.

Contrary to popular belief, you don’t need a 20% down payment to purchase a home.

Create and stick to a monthly budget

Determining and sticking to a monthly budget is crucial to successful homeownership. Beyond the mortgage payment, you’ll have to budget for repair and maintenance costs, property taxes, insurance premiums and more.

Consider “practicing” your monthly payment to prepare yourself for what it will be like to have a mortgage. Doing so can help you get a better sense of your budget so you can be financially and mentally prepared for the investment.

Pro tip: Be sure to research property taxes and insurance premiums in the area where you plan to buy. These costs can significantly impact your overall budget and limit or expand your neighborhood options.

Don’t be discouraged by a down payment

Contrary to popular belief, you don’t need a 20% down payment to purchase a home. In fact, according to the National Association of Realtors’ 2025 Profile of Home Buyers, the median down payment among first-time buyers was 10%. Also, keep in mind that some home loans may require only a smaller down payment of 3-5%.

Before you start your homebuying journey, commit to learning about the path to homeownership and make a plan to buy your dream home. To learn more about homeownership, mortgage rates, budgeting and more, visit Chase.com/Afford.

LEGAL DISCLAIMERS

* FHA loans require an up-front mortgage insurance premium (UFMIP), which may be financed, or paid at closing, and an FHA annual mortgage insurance premium (MIP) paid monthly will also apply.

** Veterans, Servicemembers, and members of the National Guard or Reserve may be eligible for a loan guaranteed by the U.S. Department of Veterans Affairs (VA). A Certificate of Eligibility (COE) from the VA is required to document eligibility. Restrictions and limitations apply.

You may be required to pay a funding fee unless the VA determines you are exempt. Exempt status is determined by the VA and confirmed through a COE. This one-time fee may be financed into your loan in most cases and is paid directly to the VA.

*** Estimated payments do not include amounts for taxes, homeowners insurance, or mortgage insurance (if applicable). Actual payments will be higher.

For informational/educational purposes only: Views and strategies described in this article or provided via links may not be appropriate for everyone and are not intended as specific advice/recommendation for any business. Information has been obtained from sources believed to be reliable, but JPMorgan Chase & Co. or its affiliates and/or subsidiaries do not warrant its completeness or accuracy. The material is not intended to provide legal, tax, or financial advice or to indicate the availability or suitability of any JPMorgan Chase Bank, N.A. product or service. You should carefully consider your needs and objectives before making any decisions and consult the appropriate professional(s). Outlooks and past performance are not guarantees of future results. JPMorgan Chase & Co. and its affiliates are not responsible for, and do not provide or endorse third party products, services, or other content. See full disclosures at Chase.com/Afford.

Home lending products provided by JPMorgan Chase Bank, N.A. Member FDIC.

Nearly 9 in 10 Millennials and Almost 8 in 10 Gen Z Carry Debt

2026-10-13T08:01:00

(BPT) – New research reveals how AI, gambling and money shame are shaping younger Americans’ financial lives.

Millennials and Gen Z are facing significant financial pressure, with many seeing their debt grow every day from increased living costs, lingering expenses and unexpected life events. For some, that pressure is shaping not only how they manage their money, but also where they turn for financial guidance and how they think about relationships, family and their futures.

A new study by National Debt Relief in partnership with Wakefield Research* shows how deeply younger Americans are challenged by debt and the stigma around it, trusting AI over loved ones, taking financial risks to pay off debt and rethinking major life decisions.

How widespread is debt for Gen Z and millennials?

Debt is widespread among younger Americans, with nearly 9 in 10 millennials (87%) and almost 8 in 10 Gen Z (77%) currently carrying debt. When looking at unsecured debt, such as credit cards, medical bills, personal loans and Buy Now, Pay Later (BNPL), more than 7 in 10 millennials (73%) and 6 in 10 Gen Zers (60%) carry unsecured debt. Credit card debt was cited as the most common.

Rising costs and unexpected expenses are the greatest contributors to that debt. Millennials cite economic factors (49%) and unexpected expenses (49%) as the most common causes of their debt in the last year, while Gen Z cites unexpected expenses (40%) as the leading driver of their debt.

Why younger Americans turn to AI for advice

Unfortunately, debt carries a stigma and feelings of shame for many younger generations that can make it uncomfortable for them to talk about. In fact, 6 in 10 millennials (60%) and a similar share of Gen Z (59%) say they’d rather publicly display their weight than their total debt. That discomfort may be one reason younger Americans are increasingly turning to artificial intelligence for financial guidance.

Nearly 7 in 10 millennials (69%) and 64% of Gen Z have used AI for advice about a financial challenge or struggle, compared with 45% of Gen X and just 23% of boomers. And 65% of millennials and 53% of Gen Z say they would feel more comfortable discussing financial struggles with AI than with the people closest to them.

This turn to AI is also influencing the financial decisions of many younger Americans. Forty-six percent of millennials and 35% of Gen Z say AI has encouraged them to make a major purchase they were uncertain about. However, traditional financial resources still rank as the most trusted source of financial guidance among both generations.

“Financial struggles can be incredibly personal, and younger adults may be looking for places where they can ask questions without feeling judged,” said Timi Joy Jorgensen, Ph.D., “The Joyful Money Doctor” and personal finance expert with National Debt Relief. “AI can be a useful starting point but shouldn’t replace trusted guidance that takes a person’s full financial situation into account.”

How younger Americans are responding to financial pressure

While some younger Americans are turning to AI for financial guidance to avoid feeling judged, the pressure they face can also lead to riskier approaches to addressing debt. Among those who regularly participate in gambling, trading and similar activities, 65% of Gen Z and 49% of millennials say they have done so in an attempt to pay off debt.

“Borrowing money to gamble in hopes of paying off debt can create a cycle that leaves people in an even more difficult financial position,” said Cathleen Bell, vice president of Customer Research & Insights, National Debt Relief. “When debt feels overwhelming, understanding your options and crafting a safer plan with an expert can offer a more sustainable path forward.”

Financial pressure is affecting major life decisions for younger Americans

Financial pressure is also shaping how younger Americans think about their futures and relationships. Nearly three-fourths of Gen Z (72%) say people should prioritize financial security even if it means not having children. Debt can also affect how younger generations evaluate potential romantic partners, with about half of millennials (49%) ranking debt among the top three things they want to know about a potential partner, more than arrest history, religious beliefs and political views.

Social payment apps can affect how younger generations perceive each other as well. One-quarter of millennials (25%) say they’ve formed an opinion about someone’s financial habits based on their Venmo transactions, compared with 17% of Gen Z and 15% of Americans overall.

These pressures are also shaping younger Americans’ expectations for their own financial futures. Nearly half of millennials (46%) and one-third of Gen Z (33%) say a debt-free life is not a reality for them.

“Financial stress can make long-term goals feel further out of reach,” said Bell. “Having a clearer picture of your finances can help you make decisions with greater confidence.”

Everyday spending can contribute to debt

Everyday purchases can also make existing financial pressures harder to manage. About 7 in 10 millennials and Gen Z with debt (71% and 69%, respectively) say convenience purchases like subscriptions, food delivery and social media shopping have contributed to what they owe, compared with 51% of Gen X and 33% of boomers.

For younger generations, the urge to “treat yourself” can outweigh financial constraints as well. Seventy-two percent of millennials and 64% of Gen Z say they’ve bought something they felt they deserved even when they couldn’t afford it at the time, compared with 36% of boomers.

Tips for handling debt

Understanding how much you owe and what is contributing to debt can help determine what steps to take. Strategies to manage debt include:

  • Take an honest look at your finances. Total your debt, income and monthly expenses so you know exactly what you owe and what you can realistically afford to pay down.
  • Build a realistic budget. Review essential and recurring expenses, including subscriptions, streaming services and food delivery, to understand your total monthly costs and identify nonessential spending that can be reduced.
  • Pay in full when possible. Whenever possible, pay your full statement balance rather than the minimum due. Paying only the minimum can mean continuing to accrue interest on the remaining balance.
  • Choose a repayment strategy. Focus on your highest interest rate debt first to save money over time or pay off the smallest balances first for quick wins that build momentum.
  • Know when to seek expert guidance. If debt feels unmanageable on your own, learning about the debt relief options available and speaking with a professional can help you determine what approach may fit your financial situation and budget.

Finding the right debt relief solution

The strategies above can help make debt more manageable, but significant debt can sometimes be difficult to address alone. In those situations, expert guidance can help consumers understand the options available and determine a path forward.

If you’re struggling with $7,500 or more in unsecured debt, National Debt Relief offers a personalized approach to resolving debt and working toward greater financial stability. The company creates a customized debt relief plan based on a client’s individual financial situation. Clients make deposits into a dedicated savings account they own and control, building funds that can be used toward negotiated settlements.

National Debt Relief works with creditors to negotiate eligible debts for less than the full amount owed. Clients do not pay a settlement fee until a debt has been successfully negotiated, the client approves the debt relief settlement, and at least one payment has been made toward it. Clients also receive access to financial education and resources to build healthier financial habits.

“Asking for help shouldn’t be a last resort,” added Bell. “For people carrying significant unsecured debt, it’s crucial to know there are solutions to help them get back on track.”

Learn more at NationalDebtRelief.com.

*Survey Methodology: The National Debt Relief survey was conducted by Wakefield Research through a custom online survey of 2,000 nationally representative U.S. adults ages 18 and older. The survey included twenty (20) content questions, along with custom screeners and demographic questions. It included responses from 550 millennial adults with oversample interviews conducted to increase the total number of Gen Z respondents to 500.
ICSC’s 2026 Holiday Intentions Survey finds consumers prioritize traditions over financial pressures

2026-10-08T07:01:00

(BPT) – Holiday spending expected to rise year-over-year as consumers increasingly seek value, compare options and borrow to cover spending

Retail sales are forecast to grow between 4.3%–4.9% this holiday season, with total expected spend topping $1.7T, according to ICSC’s 2026 holiday shopping forecast. Findings from ICSC’s annual Holiday Intentions Survey reinforce this forecast, as consumers prioritize holiday purchases and experiences above competing financial priorities.

The survey points to continued demand heading into the critical year-end shopping period. Eighty-eight percent of U.S. adults — approximately 237 million people — plan to purchase holiday gifts and other holiday-related items this season, with 78% planning to spend the same or more than last year. The top 10% of shoppers anticipate spending five times more than the average consumer, underscoring the outsized influence a small group of high-spending shoppers can have on holiday sales.

“Consumers have made it clear they are willing to make sacrifices for the things that matter to them this holiday season, but they are making careful decisions about when and where they spend to make that money go further,” said Tom McGee, President and CEO of ICSC. “Shoppers remain resilient, but they’re more discerning and value-conscious; competitive prices, convenient shopping options and experiences that bring people together are non-negotiable for retailers to attract shoppers and give them reasons to return throughout the season.”

In ICSC’s survey, 83% of consumers can keep up with their essential expenses but many acknowledge increased financial pressure. Nearly half (49%) are concerned about being able to afford holiday gifts this year and 50% say their personal or household debt will affect their holiday spending. Consumers that say concerns about the job market will affect how much they plan to spend this holiday season increased from 43% to 49% year-over-year.

As a result, many shoppers plan to make financial tradeoffs to cover their purchases. Nearly half (49%) expect to borrow money to cover purchases they cannot immediately pay for in full, while 47% anticipate holiday expenses will delay or reduce debt repayment, savings or retirement contributions. Nearly one in four (23%) expect to still be paying for their 2026 holiday purchases in 2027.

While preserving holiday traditions remains a compelling reason for consumers to continue spending, this does not guarantee loyalty to familiar retailers or brands. Fifty-eight percent expect to try a new brand, and 52% plan to shop with a retailer they have not used before. Twenty-seven percent plan more research or comparison shopping because of higher prices or budget concerns, while 25% expect to switch to lower-priced products or brands. Even among shoppers planning to spend more, more than four in 10 expect to buy fewer items, choose cheaper alternatives or buy secondhand.

Value can get shoppers through the door, while opportunities to spend time together give stores a role beyond completing a purchase. Sixty-eight percent say discounts, promotions and exclusive offers will encourage additional store trips, and 93% expect to visit a physical store to purchase an item or pick up an online order, including 97% of Gen Z.

For younger shoppers, a store visit also offers a way to enjoy the season with others. Thirty-four percent of store shoppers describe their trips as social outings or a combination of shopping, dining and entertainment. This increases to 48% among Gen Z. Half of Gen Z holiday shoppers also plan to spend more on experiences than last year, highlighting the opportunity for shopping centers to bring retail, dining and seasonal activities together.

The search for value is also shaping how shoppers plan to use AI. Sixty-one percent of holiday shoppers plan to use AI tools or assistants — up from 47% in 2025. Comparing prices is the most common planned use (29%), followed by researching products and features (19%), checking availability (18%) and finding deals (16%). Many shoppers plan to use AI as a starting point rather than a purchasing tool, with 86% intending to conduct additional research before making a purchase.

“Consumers are placing a premium on experiences this holiday season, viewing stores as more than places for transactions,” said McGee. “The human experience remains a core part of holiday shopping, and retailers that transform a simple errand into an outing or a memory are most likely to capture consumer dollars this season and beyond.”

Methodology

The 2026 ICSC Holiday Intentions Survey was conducted online from September 21-23, 2026. The survey represents a demographically representative sample of 1,003 respondents.

About ICSC

ICSC is the preeminent membership organization serving the commercial real estate and retail industries. The organization promotes and elevates the marketplaces and spaces where people shop, dine, work, play and gather as foundational and vital ingredients of communities and economies. ICSC produces experiences that create connections and catalyze deals; aggressively advocates to shape public policy; develops high-impact marketing and public relations that influence opinion; provides an enduring platform for professional success; and creates forward-thinking content with actionable insights — all of which drive industry innovation and growth. For more information, please visit www.ICSC.com.

How to travel like a foodie: Tips for planning a culinary vacation

2026-09-29T10:17:00

(BPT) – Key takeaways:

  • Culinary professionals see destinations through the lens of the cultures, seasons and agriculture that shape them.
  • Planning your travel around what grows locally and what’s in season makes for better culinary travel experiences.
  • Seek out food festivals, foraging weekends and farm-to-table wine dinners like those offered throughout agriculturally rich areas like Michigan.

One of the best parts of vacation is experiencing local foods, fresh ingredients and related customs, but how do you find authentic spots and dishes? According to people who work in the food business, there are a few tricks to uncovering great culinary moments while traveling.

1. Eat the season: Align your trip with the harvest

Freshly picked cherries from Klenk Orchards in Sparta, MI.

Freshly picked cherries from Klenk Orchards in Sparta, MI. Photo credit: Pure Michigan

Epicureans don’t just ask where to eat; they ask when. Timing your travels to the harvest or what’s in season offers a more flavorful experience. In Michigan, the second most agriculturally diverse state in America, this means seeking out peaches and sweet corn in the late summer or earthy dishes featuring foraged ramps and morels in the spring.

“I tell people to plan around produce, from spring rhubarb and asparagus to the last autumn apples and winter squash — even maple tapping season,” says cookbook author and baker Martin Sorge. “Check with local farmers to confirm when peak season is to plan your trip, and remember Northern Michigan can be several weeks behind other areas of the Midwest. You’ll find the best Northern Michigan cherries mid-to-late July, for example.”

“There’s an incredible sense of pride, community and connection to nature in Michigan’s Upper Peninsula, so I aim to let the land tell the story and guide the menu by using hyperlocal, seasonal produce and foraged goods,” says Carrie Masters, chef and owner of Bird & Toad in Marquette. “My favorite meals are often pieced together from local purveyors, and they are always best enjoyed out in nature right where the ingredients came from.”

2. Map the cultural diaspora

Wine and food pairings at a table
Culinary and beverage offerings at Highlands Detroit. Photo credit: Pure Michigan

Authentic food cultures thrive within regional enclaves. Seek out areas where immigrant populations have come to anchor the local cuisine or create fresh fusion experiences, like Detroit-area Levantine bakeries and cafés.

“Detroit has become like a mini-Los Angeles, with pockets of truly surprising and authentic international cuisine and fusions, like Mexican, Cantonese and amazing Korean-American chefs cooking the foods of their home, and adopted city,” says Matt Rodbard, an award-winning food and culture writer and editor of TASTE.

Use slow travel principles to anchor your itinerary around regional celebrations, such as harvest and food and wine festivals.

3. Anchor travel around food-centric festivals

Rather than rushing between scattered dining spots, use slow travel principles to anchor your itinerary around regional celebrations, such as harvest and food and wine festivals, like the November Art Coast Food and Wine Festival in Saugatuck Douglas. These events allow visitors to sample a wide range of local flavors at their peak.

4. Be part of the meal prep

Friends toasting each other while enjoying a Fall day outside
People enjoying Michigan craft beers and farm-to-table dining at Pond Hill Farm in Harbor Springs, MI. Photo credit: Pure Michigan

True food travel means getting your hands dirty. Seek out u-pick farms and orchards, foraging walks with resort chefs or creamery workshops, like those offered throughout Michigan’s wine coast at properties like Black Star Farms. Participating in the harvest or subsequent meal preparation builds a tangible connection to the land and makes the final dish more rewarding.

“The best culinary experiences give you a sense of place,” says Danny Simmons, director of culinary and events at Black Star Farms. “We believe in the idea that what grows together, goes together, and we build our food and wine experiences around what Northern Michigan is giving us in that moment alongside wines grown and made here. Through experiences like our hands-on cooking classes, dinners and other culinary programs, we invite guests to be part of that connection rather than simply observe it, gaining a deeper understanding of the land, the season and what pairs well together.”

5. Embrace unexpected and interesting pairings

Instead of getting that wine you always get, lean into the local beverage terroir. Pair a funky Michigan washed-rind cheese with a dry heirloom hard cider, or local Great Lakes whitefish with a crisp Old Mission Peninsula Riesling. Local wines, beers and aged ingredients are truly an artifact of the landscape.

Keep these tips in mind as you plan your next vacation. You don’t need to work in the culinary industry to uncover vibrant flavors and authentic experiences when traveling.

Photo above: People enjoying the autumn harvest at Chateau Chantal winery on Traverse City’s Old Mission Peninsula. Photo credit: Pure Michigan