Historic level of funding available to help clinicians pay off student loan

2021-03-31T13:01:01

(BPT) – The National Health Service Corps (NHSC), a federal government program administered by the Health Resources and Services Administration (HRSA), within the U.S. Department of Health and Human Services (HHS), received a historic $800 million from the American Rescue Plan Act signed into law by President Biden to support the largest clinician workforce in the program’s nearly 50-year history. The NHSC Loan Repayment Program helps medical, dental, and mental and behavioral health clinicians pay off their student loan debt in exchange for working in a Health Professional Shortage Area (HPSA) — or a defined geographic area with too few providers.

“This historic program funding for NHSC means that we will provide a record number of loan repayment awards for eligible clinicians,” says Dr. Luis Padilla, associate administrator of HRSA’s Bureau of Health Workforce (BHW) and director of NHSC. “Every community has felt COVID-19’s effects and this will allow NHSC applicants to serve in communities where they may not have been competitive to receive an award before due to sites with lower HPSA scores.”

The NHSC is currently taking applications for three NHSC Loan Repayment Programs until May 6, 2021. Eligible disciplines include physicians, nurse practitioners, physician assistants, dentists, behavioral/mental health clinicians, and more. Qualified clinicians may receive up to $100,000 in educational loan repayment, depending on the award.

Providers may apply for one of three NHSC loan repayment programs:

1) NHSC Loan Repayment Program

This two-year commitment program supports clinicians with up to $50,000 to pay off their student loan debt in exchange for service at an NHSC-approved site.

2) NHSC Substance Use Disorder (SUD) Workforce Loan Repayment Program

This three-year commitment supports the recruitment and retention of health professionals with up to $75,000. Providers must be working to combat the nation’s opioid crisis, expand access to evidence-based, medication-assisted treatment, and prevent overdose deaths in underserved areas. Applicants must work at an NHSC-approved SUD treatment facility located in a HPSA.

3) NHSC Rural Community Loan Repayment Program

This three-year commitment addresses the pressing need for qualified SUD providers in rural communities and awards up to $100,000 in loan repayment funds. Applicants must work at a NHSC-approved SUD treatment facility located in a rural HPSA.

Making an Impact

Currently, over 17 million people receive care from the more than 16,000-strong NHSC network of clinicians serving in urban, rural and tribal areas. Since the NHSC began, more than 63,000 primary care medical, dental, and mental and behavioral health professionals have served. By working with the NHSC, clinicians can help ensure access to health care for everyone regardless of their ability to pay, prevent disease and illness, and care for the nation’s most vulnerable people.

To learn more and apply for NHSC’s Loan Repayment Program, visit NHSC.HRSA.gov/loan-repayment/.

Pursuing a mortgage with ‘less-than-perfect’ credit

2021-03-31T07:01:00

(BPT) – Owning a home is the cornerstone of the American dream. There’s nothing like having a permanent plot of land you can call your own.

But, if you’ve hit a rough patch with your credit score, this dream might feel like it’s out of reach. However, finding a suitable mortgage with a “less than perfect” credit score is still possible.

Is there a minimum credit score for mortgages?

Typically, there isn’t a minimum credit score required for mortgage applications. However, recent blending of government policy and business practice have resulted in a current credit score threshold of around 620. But some lenders may have the power to determine their own score acceptance limit. This can make it hard to find the institution where you may qualify, as each lender operates a little differently. No matter where you’re at in your path to homeownership, or what your score is, here are a few tips to help you secure that mortgage:

Exercise all of your options

If you’ve had lenders reject your conventional mortgage application, there is no need to worry. That’s because there are several loan options available aside from conventional mortgages. Some of those include:

  • FHA loans: This is a loan provided by an FHA-approved lender and while there are no maximum income limits on an FHA insured loan, they have typically been used for first-time homebuyers or low-to-moderate income borrowers. The loans are insured by the Federal Housing Administration. FHA loans require a small down payment (typically 3.5%) and will frequently accept borrowers with lower credit scores.
  • VA loans: For current and former members of the military, a VA loan can be a viable option for securing a home. VA loans typically don’t require any down payment; are partially backed or guaranteed by the Department of Veterans Affairs; and are frequently made available to active duty or former members of the military with lower credit scores.
  • USDA loans: Like FHA loans, these are frequently made to low-to-moderate income individuals with low to moderately low credit scores. However, to qualify for a USDA loan, your home must be in a USDA-designated suburban or rural location.

Work to improve your credit

If you’re not interested in utilizing a government-backed loan such as FHA, VA or USDA, improving your payment habits, thereby boosting your credit score, can be another viable option. Even if it takes time to raise your credit score a few points, it can still be beneficial. You can boost your score by making consistent, on-time payments, and finding ways to diversify your credit mix or lower your overall credit usage.

Buy within your means

Even if you have a bad credit score, lenders will perceive you as less of a risk if you stay within your means when buying a home. Lenders will likely analyze your income to obligations closely to see if you have leftover reserves every month (which they refer to as “residual income”) to help absorb the shock of unexpected expenses. Do your best to save as much as you can for a down payment, but remember — private mortgage insurance can help minimize a down payment shortage.

Don’t give up

While the mortgage qualification process can be challenging, it’s essential to stay vigilant. If it looks like you’re going to get a “no” at first, it might just mean more work needs to be done to evaluate your situation more deeply. Many times, a “no” is really a “not just yet.” But with persistence, patience and passion, you can still achieve your dream of homeownership.

Learn more about what your score looks like and examine the factors using VantageScore’s consistent, accurate and inclusive scoring models at https://vantagescore.com/consumers/our-models.

Business credit scores: 6 things every entrepreneur should know

2021-03-31T07:01:00

(BPT) – Do you have a side hustle you’re looking to grow? Are you a small-business owner wondering if you should use your personal credit for your business? Before you do, consider your business credit score. Whether it’s a modest side gig or you’re looking to expand your small business into a full-time, multi-person venture, it’s important to understand your business credit score and how it can help you.

Haven’t heard of a business credit score? You’re not alone. “What is a business credit score?” is the top question we get at VantageScore from small-business owners. Our goal is to expand understanding about credit scores for everyone, and when it comes to businesses, helping empower owners with useful information to help them make smart financial decisions.

The credit experts at VantageScore Solutions share must-know info about business credit and how small-business owners can establish and grow their business credit score:

Consumer and business credit reports are different

A consumer credit report is for an individual while a business credit report is for an organization, even if it’s just one person. What’s on the report varies: A business credit report has different number ranges for credit ratings, such as zero to 100. Additionally, you won’t see a list of creditors on a business credit report like you would on a consumer credit report.

A positive business credit report matters

A business credit report shows credit-related data a credit reporting company (CRC) has gathered about an organization from different qualifying sources. This includes records of credit card balances and payments, as well as public records, such as bankruptcies. Having a rich business credit report can help you get better terms on business loans and other financial relationships needed to manage and grow your business, including lower interest rates.

Be proactive to strengthen your business credit report

If you get a consumer loan, that information may be reported to all three bureaus for your consumer credit report. On the business side, there’s less data consistency and less chance your lender is going to report to all the commercial credit bureaus. Be proactive by using strategies that include reporting to the bureaus, such as utilizing small-business credit cards. You can also work with vendors that knowingly report to the bureaus. Finally, as always, pay all bills on time and keep debt low.

Separate yourself and your business

Just like with consumer credit, it takes time to build a rich credit history. Business owners should start building good credit as soon as possible and start by establishing a business entity. The majority of small-business owners in the United States operate as sole proprietors, which means they don’t have a formal business structure such as an LLC, S-corporation or C-corporation. Having these types of designations separates you and your business and therefore separates your business and personal credit.

Avoid tapping personal assets

When starting or growing a business, a lot of people use personal assets such as savings, retirement funds or home equity for funding. Before you do this, exhaust all other possibilities for business financing. There are over 6,500 different companies with lending products for small-business owners, so it’s worthwhile to research and find one that fits your needs so you don’t have to put your personal finances at risk. Plus, many of these other options come with the opportunity to build your business credit report.

Check your business credit report regularly

Just because you pay your bills on time doesn’t mean you should assume your credit report is good. If something negative occurs, you want to respond quickly, such as financial fraud or identity theft. Visit VantageScore.com to access a list of free credit score providers for both your personal and business credit reporting purposes.

How to crush interviews and build relationships — even through a screen

2021-03-26T14:01:00

(BPT) – Have you been on a recent virtual date or job interview and just not felt the energy you might have in person? You’re not alone — as the pandemic has taken away the ease and safety of in-person meetups, “Zoom fatigue” has become a regular part of our vocabulary. Sometimes, trying to connect with someone through a webcam just doesn’t feel right, but the good news is that there are solutions.

Some people have mastered the Zoom life and have some tips to share about how to foster really meaningful personal interactions, even through a screen.

“You’ve got to let your curiosity fuel you,” says OZY CEO Carlos Watson. As host of the viral YouTube talk show sensation The Carlos Watson Show, Watson has created the warmest place on the internet, where his uniquely charming conversation style leads to some of the most intimate conversations with the world’s biggest names. “Don’t think of it like you’re miles away; appreciate the intimacy Zoom brings — you’re in each other’s homes.” And while Watson has invited TV’s most diverse lineup to his virtual coffee table, boasting names from Ava DuVernay to Mark Cuban, John Legend to Megyn Kelly, here are his top tips for anyone trying to get past Zoom fatigue and create real relationships over calls:

Start in a place of mutual understanding

Having interviewed everyone from President Obama to Karl Rove, Tomi Lahren to Rep. Ilhan Omar, Watson knows he might not agree with every guest, but emphasizes the importance of finding common ground. “It feels like one of the most divisive times in history, but we need to remember that there’s more that connects us than divides us,” he says. Try to find something you do agree on or a mutual friend or favorite activity. Starting things off on the right foot will allow the rest of the conversation to go more smoothly.

Have an open mind and no expectations

Don’t approach a new conversation with expectations, because you may be disappointed if they’re not met. But an open mind allows conversations to take whatever serendipitous turn they might. Watson knows this, and covers a notable range of topics with the world’s top names. Let your conversations wander, because you never know where they might take you.

Surprise yourself with creative questions

Along with avoiding presuppositions of the conversation, avoid presupposing what your conversation-mate might be interested in talking about. In his show, Watson focuses on asking creative questions. He might talk about love with politicians, politics with musicians and music with athletes. Whether on a virtual date or job interview, the likelihood is the person you’re talking to is used to getting similar questions and doesn’t get to be creative with their answers. By thinking outside the box with the questions you ask, and pivoting from the norms, you can get the most genuine answers.

Hopefully you feel prepared to tackle that next Zoom interview or ask your Hinge date for a virtual coffee. And make sure to check out Carlos Watson’s expertly charming conversations on The Carlos Watson Show.

Find a Small Business Tax Pro You Can Trust: 3 Questions You Must Ask

2021-03-23T14:37:00

(BPT) – Managing your small business will be one of the hardest things you’ll ever do! Turning your dream into a reality takes more than courage — it takes hard work, planning, diligence and trust. Trust is paramount because you’ll have to outsource much of the work involved, unless you’re also an expert in technology, marketing, payroll, insurance, bookkeeping, small business taxes and myriad other professions.

But who can you turn to for help? Your fallback will be to ask your friends, family and professional network for recommendations. And while that may work for some things, for more complicated business issues, like small business taxes, it’s important to look for someone with experience in your industry who has the credentials and training needed to help your business succeed.

You’ll also want to find someone who can help you year-round with tax questions and other financial tasks so you can focus on running your business. If you know what questions to ask from the start, you’ll avoid potential headaches and pitfalls along the way.

What’s your small business tax background?

First, determine a tax advisor’s credibility by asking about their specific small business tax background. Just because someone has prepared individual tax returns doesn’t mean they’re qualified to do your small business taxes. Also, years of experience matters, because they’ve had more time to learn about the credits and deductions available for small businesses.

For example, Marcie Rahn is a small business certified tax pro with Block Advisors. She is also an IRS Enrolled Agent (EA) with a Master of Accounting degree who’s prepared more than 500 returns for small businesses. Who would you be more inclined to trust with your business: Marcie, or your mom’s accountant (“the nicest guy in the world”) who doesn’t have small business tax experience?

You should also know the tax preparer’s area of expertise. Because you want advice that goes beyond tax theory and gets into applied, real-world experience. Think of it as ‘street-smarts’ for small business taxes.

How do you stay up-to-date on the latest tax laws and changes?

Tax laws are complicated, and they change every year, so you’ll want to find a tax advisor who understands the changes and can keep your business up-to-date and compliant. If you’re reluctant to ask this question, start by looking for a reputable company that invests in education and training for its tax advisors, like Block Advisors, a team within H&R Block.

Block Advisors tax pros have an average of 12 years of experience and hundreds of training hours, along with mandatory annual continuing education that is unique to the needs of self-employed individuals, small business owners and S Corp structures.

What are your professional credentials?

Some people will advise you to work with a Certified Public Accountant (CPA) for your small business taxes. That might be good advice, but remember, CPAs are accounting professionals who offer a range of financial services, including tax preparation and filing.

Other credentials qualify people to prepare small business taxes as well. For instance, Enrolled Agents (EAs) are tax professionals credentialed by the IRS or who have worked at the IRS for a minimum of five years.

Tax return preparers aren’t required to have professional credentials, although any person authorized to prepare a tax return for a fee needs to have a Preparer Tax Identification Number, or PTIN.

Many Block Advisors small business certified tax pros are CPAs or EAs and all have gone through specialized training to serve the unique needs of small business owners across a wide range of industries.

“Our proprietary small business certification is only available to our most senior tax specialists,” said Ian Hardman, Vice President and GM of Small Business at H&R Block. “These senior advisors seek this additional level of certification to demonstrate their continued devotion to helping small business owners succeed. It also signifies a consistent level of outstanding service across nearly 8,000 locations nationwide.”

Marcie Rahn shares a few other words of advice with aspiring small business owners.

“Look for someone who can take the time to help you lay the groundwork: how to keep good records, how to understand a profit and loss statement, how much to set aside for taxes. Also, look for someone who cares about your success: who asks about your dreams and goals, and what success means to you. You want someone who feels vested in your success, so that they take the time to help you make the most tax-savvy decisions and squeeze the most out of every deduction,” said Rahn.

Block Advisors, a team within H&R Block, is dedicated to meeting the tax, bookkeeping and payroll needs of small business owners year-round. To start working with the tax experts at Block Advisors, visit blockadvisors.com.

Choosing the right tax preparer

2021-03-19T13:17:00

(BPT) – Financial confidence for many Americans begins with the tax refund. And, it’s less about total household income, and more about knowing what to expect at tax time — especially when it comes to your refund.

The good news is there are opportunities to take control of your finances to become more confident, including planning around your tax refund and finding the right qualified tax preparer who will help you get every credit and deduction you deserve.

Here are a few questions you should be asking when selecting a tax preparer:

Do you have a preparer tax identification number (PTIN) and how do you stay current on taxes?

Paid tax return preparers are required to have a current PTIN. Your preparer must sign the return and include their PTIN before it is filed. In addition to whether they have a PTIN, you should ask about what education courses they take to stay up-to-date on tax law or what professional organizations they belong to.

“Tax law changes annually, and this year, with COVID-19 relief bills, we saw even more changes than usual,” said Andy Phillips, director of the Tax Institute at H&R Block. “In fact, an H&R Block study found that 56% of Americans have more tax questions than last year due to the pandemic. A qualified tax professional can help you make sense of the many tax law changes and how they impact your specific situation to help you get the best outcome.”

How do you protect my information?

Look for a preparer who has safety protections in place to keep your data and your identity secure. In a year when more people will work with tax preparers remotely, this is especially important, Phillips says.

H&R Block uses myBlock, a secure client-data portal, to safely share documents between clients and their tax professionals.

Are you available year-round?

In addition to protecting your data, you want to find a tax professional who can help you year-round in case you need to amend a return or if the IRS comes back with questions. The myBlock app allows you to get tax return updates, store your tax documents, connect with a tax pro year-round, and plan for next year.

“If a letter from the IRS arrives, don’t panic. Make sure you read it clearly and understand your next steps,” says Phillips. “If you don’t feel comfortable responding to the notice or need help figuring out what it means, you won’t have to go it alone if you have a tax preparer who is available year-round.”

At H&R Block, you can work with its tax pros every year so they can better understand your unique tax filing situation. More than twenty million Americans trust H&R Block professionals and software each year to prepare their taxes and help get their maximum refunds.

Working with an H&R Block tax pro is easy and they can help no matter how you want to do your taxes. You can drop your documents off at a local office or securely send a pic of your docs, and when they finish your review you can approve it online. Get started at hrblock.com.

4 Smart Money Moves Small Business Owners Should Make from the Start

2021-03-15T18:15:00

(BPT) – Most small business owners start their business to pursue a passion, not to crunch numbers. However, it’s important to get the finances right in the beginning to have the best chance at success. If you’re not a numbers expert, you may need the help of an experienced professional, because accurate taxes and bookkeeping can help you avoid missed deductions or costly mistakes.

“If you’re thinking about starting your own small business, also think about getting help from day one,” said Ian Hardman, General Manager and Vice President of small business at H&R Block. “Block Advisors small business certified tax pros can help you make sound tax and financial decisions, guiding you to better outcomes so you can focus on what you love.”

Here are four smart money moves to make when starting your small business.

Secure funding

It costs money to start a business, so if you can’t personally cover your start-up costs, you’ll have to secure financing. This can be difficult, yet proper financing is one of the most important elements a company needs to succeed. Also, how you choose to finance your business could impact how you structure and run your business.

There are numerous financing options — not just the traditional bank loan. In fact, the U.S. Small Business Administration (SBA) outlines several small business funding options. One thing to note: you’ll need a strong business plan and an accurate view of your financial situation and runway before you start.

Choose the right entity structure

Your business structure impacts everything from your day-to-day operations to your taxes and personal liability, so it’s important to choose the business structure that provides the best legal protection and least amount of tax responsibility for your business type. Many small businesses start as a sole proprietorship or limited liability company (LLC). However, do your homework before deciding which structure makes the most sense for your business.

Set up a business bank account

Separating your business and personal finances is a must. It’ll make your accounting, quarterly, and end-of-year tax filings easier if there is a clear divide between your business and personal funds. Plus, a dedicated business account helps provide proof to the IRS that you’re running a legitimate, money-making operation.

Before deciding to open a business bank account, evaluate your options to identify banks that specialize in helping new and emerging businesses. H&R Block’s subsidiary, Wave Financial, offers a business bank account and debit card with built-in bookkeeping, with no monthly fees, account minimums, transaction fees, or ATM withdrawal fees if you withdraw from its network of 55,000 surcharge-free ATMs. Wave Money offers fast access to payments, automates bookkeeping and creates tax-ready records, freeing entrepreneurs from time-consuming administrative tasks.

Track your start-up expenses, including mileage

Every dollar counts when you’re a small business owner. If you’re even thinking about starting a business, keep track of your miscellaneous expenses, including mileage, while you explore your options. You won’t get to deduct these costs immediately, but when your business flips the “on” switch, you may be able to capture them on your taxes as start-up expenses.

If you use your car for both personal and business purposes, you must divide expenses based on the percentage of actual mileage driven for each use. Using a mileage and expense tracking app, like Everlance, can make it easy, both on you and your tax advisor. Block Advisors and Everlance have partnered to offer small business owners an opportunity to save money — discounted tax prep with an Everlance premium account.

“We understand that the financial aspects of running a small business can seem overwhelming, but Block Advisors can be your partner in figuring it out. We’re here to help take on some of those important financial tasks so you can focus on building your business,” Hardman said.

Block Advisors, a team within H&R Block, is dedicated to meeting the tax, bookkeeping and payroll needs of small business owners year-round. To start working with the tax experts at Block Advisors, visit blockadvisors.com.

Our small business tax professional certification is awarded by Block Advisors, a part of H&R Block, based upon successful completion of proprietary training. Our Block Advisors small business services are available at participating Block Advisors and H&R Block offices nationwide.

Ireland ranked No. 9 for foreign direct investment into the U.S. economy

2021-03-15T11:01:00

(BPT) –

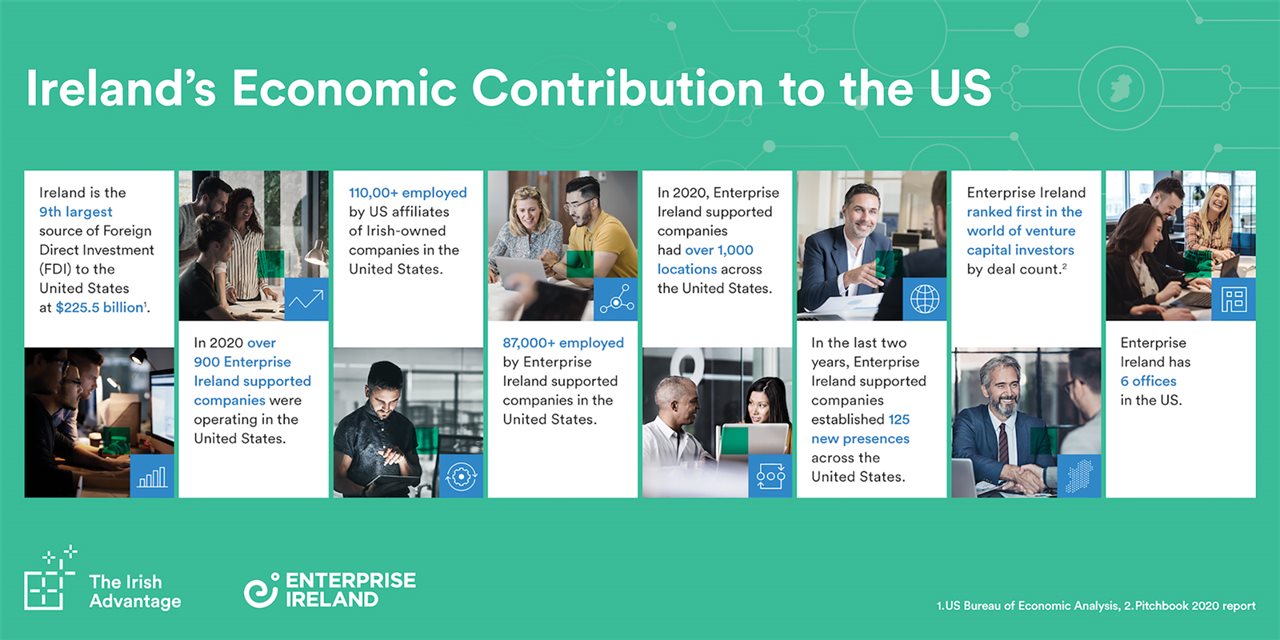
Enterprise Ireland, the Irish government agency for the international development of Irish firms, reports employment by Irish businesses in the United States has reached 110,000 and foreign direct investment from Ireland into the United States economy hit $225.5 billion* — ranking Ireland in the top nine investment sources to the United States. The strong performance of Irish businesses in the United States was accelerated by resilience and preparedness developed in response to the 2016 Brexit referendum. Additionally, Ireland’s considerable strengths in life science and construction, engineering, smart energy, smart city and digital technology enabled Irish firms to support the U.S. government and business roll-out of COVID-19 remediations. According to an OECD report, Ireland is fifth in the world for the export of COVID-19 related products and services and sixth in the global market of countries responding best in terms of innovation to the pandemic.

“Irish innovation and entrepreneurship shone brightly in what was a dark year,” the Taoiseach Micheál Martin, Prime Minister of Ireland, said today. “I am highly encouraged by the resilience of Irish business leaders and their teams and I am proud of the positive impact they’re having in their business communities in the United States. 2021 promises to be a generation-defining year in the development of U.S.-Irish business partnerships. I am confident that Irish firms operating here will continue to advance the COVID-19 response, sustainability initiatives and infrastructure, and that we’ll see continued job growth and an increase in Irish FDI into the United States economy.”

Over 100 Enterprise Ireland-supported companies are responding to the pandemic with innovative solutions. Highlights include:

  • In New York and New Jersey, Nearform was one of the first to develop and launch a COVID-19 contact-tracing app for government agencies and has since become the official COVID-19 app of several U.S. states.
  • Irish biometric authentication solutions provider Daon has created VeriFLY, a mobile health passport. American Airlines is the first U.S. airline to adopt the VeriFLY technology, providing customers with an easy method of providing results from a negative coronavirus test and other completed documents required for international travel into the United States.
  • From Monaghan, forklift truck manufacturer, Combilift, developed the Combi-Ventilate, a splitter device that can turn one ventilator into multiple ventilator stations.
  • In Tampa, Shimmer Sensing, a leading provider of wearable wireless sensor products and solutions, partnered with the University of South Florida to research how Shimmer’s wearable device can help detect and assess the progression of COVID-19 in those who are most at-risk.
  • In Illinois, Druid Software, recognized as a market leader for its mature 4G & 5G LTE Private Cellular technology, helped deploy a CBRS enabled OnGo Private 4G wireless network at Memorial Health Systems to provide secure, reliable connectivity to temporary triage and testing tents where doctors and nurses delivered emergency care during the COVID-19 outbreak.

“Ireland’s sustained positive contribution to the United States economy in a year of unprecedented turmoil is a testament to the depth of trust between our business communities; the quality of commercial relationships and the value that Irish firms bring to the United States,” Julie Sinnamon, Chief Executive Officer, Enterprise Ireland said today. “Now, with vaccine deployments taking hold and green shoots emerging in the economy, the indicators point to Irish firms investing even more time and resources into the United States.”

Over the past year, Enterprise Ireland saw an average of two new Irish-based businesses established weekly in the United States. In 2020, Irish firms bolstered employee rosters in traditional hubs of Irish entrepreneurship in San Francisco, New York, Chicago, Los Angeles, Boston and Philadelphia, and also in Irish firms in Florida, Texas, Georgia and Minnesota.

“The fact that so many Irish firms sought to strengthen their United States presence in a WFH business environment underscores the confidence Irish firms have in themselves and in this market,” Sean Davis, North America Regional Director, Enterprise Ireland said today. “This bold new confidence is forged on conviction in the products and services and also informed insights on the needs and preferences of United States partners and customers.”

Enterprise Ireland is one of Europe’s leading venture capitalists: the agency is ranked first both in Europe and globally for active seed investments, according to PitchBook. Enterprise Ireland operates from New York, Boston, Austin, Chicago, Seattle and San Francisco. In addition to funding support, Enterprise Ireland also provides services including export assistance and assistance with research and development, as well as a broad network of key global industry-specific contacts.

More than 110,00 people are employed by almost 900 Irish-owned companies with Enterprise Ireland representing 700 of these companies in the United States. These Irish-owned companies operate across all 50 states and proudly represent a broad range of industries including construction, education, energy, environmental engineering, medical devices and software.

About Enterprise Ireland

Enterprise Ireland is the Irish State agency that works with Irish enterprises to help them start, grow, innovate and win export sales in global markets. Enterprise Ireland partners with entrepreneurs, Irish businesses, and the research and investment communities to develop Ireland’s international trade, innovation, leadership and competitiveness. In this way, it supports sustainable economic growth and regional development, and helps create and sustain employment in Ireland. For more information, please visit IrishAdvantage.com.

###

*The United States Bureau of Economic Analysis.

3 reasons why you might have missed out on stimulus money and what to do

2021-03-12T10:39:00

(BPT) – At a time when people are struggling financially in the wake of the COVID-19 pandemic, they may have also missed out on all or part of their first and second full stimulus payments, money intended to help during a critical time. New parents and recent graduates could have unknowingly missed out on stimulus money and could claim a credit when they file a tax return.

Specifically, the first two stimulus payments were calculated using 2019 tax returns and for some people on 2018 returns, meaning the IRS wouldn’t have known about 2020 life changes such as adding new dependents, becoming a first-time filer, or reduced income if they didn’t receive the full amount. These individuals are likely due additional stimulus payments with the help of the 2020 Recovery Rebate Credit.

“COVID has impacted nearly everyone’s taxes. As you navigate the recovery rebate credit and your tax situation you can get help online, virtually or in person from H&R Block’s highly trained tax pros,” said H&R Block Chief Tax Officer Kathy Pickering. “Working with a tax pro can help you feel confident that you can receive your full stimulus amount added to your refund.”

Reasons to use the 2020 Recovery Rebate Credit to claim missed stimulus payments:

1. Unemployed or reduced income in 2020

For people whose income was above the income caps for the first and second stimulus payments but whose income was reduced in 2020 to under the income caps, additional stimulus payments via the 2020 Recovery Rebate Credit may be available. To understand more about the tax implications of unemployment benefits, visit H&R Block’s unemployment and taxes resource center.

2. Expanded family with a new child

Many things happen in life that the IRS doesn’t know about until a tax return is filed, including having a baby, adopting or fostering a child. Approximately 3.7 million babies were born in 2020 and roughly 140,000 children adopted[1] in the United States. Families who added a child not previously claimed as a dependent on their tax return may be eligible for additional stimulus money.

3. First-time filers like recent college graduates

According to the Department of Education, 5.7 million students received high school or undergraduate degrees in 2020. Those starting careers will become first-time filers and likely can’t be claimed as a dependent, possibly making them eligible for stimulus money. For example, if a college graduate was a dependent in 2019, graduated and moved out on their own and started a new job, they are likely eligible for the 2020 Recovery Rebate Credit.

For help in understanding a tax situation and to find out more about who may be eligible for additional stimulus money, find a tax pro at hrblock.com. There is no additional cost for claiming a Recovery Rebate Credit whether a client chooses to get help from our experts or to do taxes on their own, including in H&R Block Free Online.


[1] Adoption Network, U.S. Adoption Statistics.

3 issues many working women face today

2021-03-08T08:01:00

(BPT) – Even though women make up nearly 51% of the world’s population, there is still a way to go when it comes to full, fair and equitable treatment.

As part of International Women’s Day and Women’s History Month, Mars, Incorporated, a global, privately held and family-owned company with a diverse and expanding portfolio of confectionery, food, and pet care products and services, is looking for ways to create more equitable communities in and out of the workplace by asking what is needed to help more women reach their full potential.

“Increasingly business is being called upon to make a lasting, positive impact on society. In that spirit, Mars wants to hear from diverse voices — women around the world and men who champion progress — on what needs to change in order for women to reach their full potential,” said Jessica Adelman, vice president corporate affairs, Mars North America.

Here are a few of the outside factors that serve as barriers to women and how companies everywhere can help solve the issue, because we all have a role in creating a better world tomorrow.

For mothers, childcare is expensive

According to a recent report, it costs on average $16,000 annually to raise a child in the United States. Some states are more expensive than others. But in many cases, that amount is more than annual tuitions at flagship universities. And for women who decide to leave the workforce to care for their children, those annual costs can create extra burdens long-term.

How can employers help? Employers who can afford to should consider childcare subsidies for working parents, or provide back-up care resources. These options can allow women to stay in the workforce and provide for their children, or elderly relatives, without unnecessary sacrifice.

When it comes to parental leave, Denmark is known for having some of the best child care policies in the world. In Denmark, women can get a total of 18 weeks paid maternity leave. Four weeks before the baby is born and 14 weeks after. Parents split 32 additional weeks of leave after that.

Work schedules can be restrictive

With countless professionals working from home, many have realized the traditional 9-5 isn’t feasible while balancing other responsibilities. That’s especially true for women, who take on the lion’s share of caregiving work inside the home. Not only are they trying to keep up with work-related duties, but they’re also more likely to take responsibility in caring for children or supporting aging parents. The burden is even more significant for single working mothers.

To combat this, employers can offer flexible work schedules. A flexible schedule can allow women to tend to the needs of themselves and their family while allowing them to do their jobs to the best of their ability.

Our collective mental health is taking a hit due to the pandemic

Lots has been written a year into a global pandemic about how women are reporting significantly higher levels of psychological distress due to the burdens and societal expectations placed on them, especially during times like these.

Employers need to understand the mental toll the pandemic is taking, not only on women, but on all of their employees, and find ways to help them cope. Whether that’s through free or discounted therapy sessions, yoga classes or family leave, there’s a lot they can do. In the U.S. Mars adapted its previously in-person employee well-being moments such as stretch breaks and fitness classes to a virtual format, offering a way for employees to connect with each other virtually, support their mind and body, and invite more employees than before to join in without the limit of a physical room.

Finding solutions requires working together

The pandemic has created fear and uncertainty for people around the world. However, it has also shed light on the daily struggles of women and given them a voice to fight for more fair and equitable treatment in the workplace and beyond.

Mars is one of the many companies joining in the fight for workplace and societal equality for all women. That’s why the company is using its voice to stand up not just for its employees, but for all women around the globe. However, this requires collective input. People need to share their stories and raise their voices if society is to create strong and thriving communities not just for women, but for everyone around the world.