Everyone can save on vital energy costs

2020-10-21T08:49:50

(BPT) – It’s something everyone in the U.S. needs and uses in their everyday lives — energy to keep the lights on, appliances working and homes cool or warm enough to be comfortable. Now that Americans are spending more time at home, energy needs — and costs — for households across the country are going through the roof.

And unfortunately, energy costs tend to be higher for families already struggling with lower incomes and job insecurity, along with other challenges due to the pandemic. According to the American Council for an Energy-Efficient Economy, low-income, African-American, and Latino households and renters pay up to three times more on energy costs as a proportion of their income.

The result? Some low-income households spend nearly 20% of their income on utility bills, which adds to the challenges already affecting these families as they struggle to make ends meet.

What’s being done to help ease energy burden?

The ENERGY STAR Program and its many partners in the private and public sectors are working to bring the benefits of energy savings to everyone — especially those who need it most. Products that earn the ENERGY STAR label meet strict energy-efficiency specifications set by the U.S. Environmental Protection Agency.

In addition to providing energy-saving products and services, many ENERGY STAR partner organizations are working to increase access to energy efficiency and deliver assistance to consumers through:

  • Lower prices and rebates offered on ENERGY STAR certified products including HVAC systems, smart thermostats, water heaters and household appliances.
  • Local utility company programs helping families save energy through income-qualified services, such as free home energy audits and other resources for cutting energy usage and costs.
  • Programs assisting low-income families and providing education around energy efficiency include:
    • LED bulb giveaways and donations from utility companies around the country, focusing on communities hardest hit by the pandemic.
    • Energy assistance programs to help homeowners keep and maintain their homes.
    • Teen tech centers to offer safe after-school spaces where teens can learn tech skills and engage with schoolwork.
    • STEM-based educational programs to boost interest in science, technology, engineering and math.

Programs and opportunities like these can help your family save on energy costs, while also helping you and your children learn about new energy solutions and even emerging careers in fields that will create a more energy-efficient future. Go to energystar.gov/saveforgood to find out what’s available near you.

How much can you save?

When you take advantage of energy-efficient solutions, the exact amount of energy and cost savings — and benefit to the environment — will vary, depending on the appliance and how much it is used.

But the overall numbers tell the story: Since 1992, ENERGY STAR and its partners have helped American families and businesses save more than 4 trillion kilowatt-hours of electricity, and achieve over 3.5 billion metric tons of greenhouse gas reductions.

In 2018 alone, ENERGY STAR certified products helped consumers:

  • Save 430 billion kilowatt-hours of electricity
  • Avoid $358 billion in energy costs
  • Achieve 330 million metric tons of greenhouse gas reductions

What does that mean for your family? A typical household spends about $2,000 per year on energy bills. With ENERGY STAR certified appliances, you can save 30% or about $575 — while avoiding over 5,500 pounds of greenhouse gas emissions. A typical household equipped with ENERGY STAR certified products can reduce greenhouse gas emissions by over 77,000 pounds of CO2 and save about $8,750 on utility bills over the life of these products.

Get started with your home

In honor of ENERGY STAR Day, Oct. 27, explore the benefits of greater energy efficiency for your household, including savings on energy and money, while also helping protect the planet.

Learn more about how ENERGY STAR and its partners can help by visiting energystar.gov/saveforgood.


Saving in Uncertain Times

2020-10-19T13:01:01

(BPT) – The savings habits of Americans appear to be shifting in light of the challenging circumstances of the past few months. In addition to shoring up personal savings, there are indications that Americans are reforming their habits in other key areas like healthcare and retirement as they plan for an uncertain future. This newfound diligence represents an evolution of the approach that many had adopted in regard to savings and financial resilience. In response, financial services providers are producing innovative new tools for savers to steady their income amid the turbulence of 2020. Increasingly, these financial providers offer members of key affinity groups special products and services.

Personal Savings

The evolution in savings practices comes at an opportune time; an unprecedented abundance of options means that many have a better ability to improve their savings habits. There is no shortage of data showing many Americans remain unable to handle a sudden, unexpected expense: a January 2020 survey showed that nearly 4 in 10 Americans were unprepared to cover an unexpected $1,000 expenditure, while a 2019 poll revealed that 74% of U.S. workers live paycheck to paycheck.

The good news is that tide may now be starting to turn. Newer data released this spring revealed that American savings account balances are at record highs. From healthcare savings accounts (HSAs) to income-generating retirement vehicles and high-yield savings accounts, individuals are more than ever appreciating the importance of a nest-egg, and companies are rolling out new options to meet customers where they are. One prominent industry example, Marcus by Goldman Sachs®, is offering AARP members a special rate on a no-fee, high-yield Online Savings Account and an exclusive 8-month term on a No-Penalty CD. Their No-Penalty CDs offer a fixed rate with the option to withdraw the full balance beginning 7 days from funding without a penalty.

Healthcare Savings

Health savings accounts (HSAs) were created as a way to help consumers save and plan for health expenses. As increasing healthcare costs began to comprise a greater portion of the average household budget, it became necessary for consumers to prepare for unexpected medical expenses in a more flexible and tax advantageous way. Financial institutions quickly started to realize the potential of healthcare savings plans, and today research shows HSA growth remains strong with $73.5 billion in assets held in more than 29 million accounts.

“An HSA provides more than medical cost savings,” said Paul Leary, Head of Health Benefit Accounts at Optum Financial. “It’s a smart investment option that can help you build a financial plan and prepare for unexpected health costs. The money goes in tax-free, grows income tax-free and comes out income tax-free when you use it for qualified medical expenses. HSAs are portable and have no ‘Use it or Lose it’ rule, so these dollars can be accessed at any time.”

Optum Bank also offers an HSA product that’s exclusive to AARP members.

Retirement

As the retirement savings industry has grown, the limitations of traditional offerings have become more apparent. Specifically, the decline of pensions and rise of 401(k)s has given Americans the opportunity to take a more active role in planning for the future. This has led to the increasing availability of guaranteed retirement income and guaranteed return products.

Providers such as Blueprint Income now offer annuities for those both approaching and in retirement. Special benefits, such as a free annual retirement income checkup, are available to AARP members. Customers capitalize on their existing savings for a guaranteed source of income later in life, providing a level of stability not offered by the market. As the retirement savings industry grows in size and complexity, guaranteed income solutions may become a staple for savers.

Personal savings have never been more important as Americans face the stark reality of a struggling economy. Demand for innovative savings products will continue to evolve as consumers strive to build short-term savings and fund retirement income for today’s longer lifespan.


Expert Series: Time to Check Your Benefits: Work with a Professional on a Pre-Retirement Financial Wellness Assessment

2020-10-16T09:01:00

(BPT) – By Jon Anderson and Kaci Skidgel

With so many decisions to make this time of year about your employee benefits, it’s an opportune moment to think more broadly about your overall financial wellness too. This may seem like a daunting task, but fortunately you’re not alone. A financial professional is armed with the experience and knowledge to help you make these important decisions (more on this later). So, while you’re working with that person to review health plans and options for flexible spending accounts as open enrollment deadlines loom, take time to think about your longer-term goals, including your retirement savings plan.

There’s no single best time to begin plotting your path to retirement, but the prevailing wisdom is the sooner the better. Especially when there’s economic uncertainty, like there is now amid the ongoing coronavirus pandemic, it’s in your best interest to balance short-term and long-term financial goals and to develop a plan for your eventual exit from the workforce.

Whether you’re well on your way toward your retirement savings goals or just getting started, there are some tried-and-true steps for setting yourself up for a bright financial future.

Seek professional guidance. If you’re like most people, you know about the importance of saving for retirement but less about the ins and outs of the planning process or where to put your money. In fact, most Americans nearing or entering retirement are not steeped in all the options and advantages for retirement savings, according to the latest Retirement Income Literacy Survey by the American College of Financial Services. If there are any up sides to the lockdowns we’ve experienced in recent months, it’s that people have dedicated more time and attention to evaluate their financial needs and have looked for advice. According to the survey, conducted earlier this year, nearly 6 in 10 respondents relied on financial professionals to help them set goals and devise strategies for their retirement savings. Working with a professional who understands the risks and benefits of all your investment options can help demystify the process, ease your anxiety and provide you with a better informed and successful plan. You might start with one of the regular retirement planning sessions provided in your area for free or low cost, and delve into the array of programming and tools that are easily accessible online. That can help you find a financial professional who fits your needs and preferences.

Set a goal and weigh your savings options. The most effective way to kick off your effort is to figure out how much you will need to live comfortably and then begin investing your money in one of the retirement plan options available to you. When estimating your goal, you and your financial professional will need to determine when you will retire and estimate what your expenses will be. After adjusting for income you expect from Social Security and other sources you will have an idea of how much you will need to save yourself.

Find out what plans are available through your employer and how to take full advantage of any tax benefits and matching contributions they offer. (If your employer matches your contributions — essentially free money toward your retirement — strive to contribute up to the maximum, or more.) You can also explore individual retirement accounts, or IRAs, or other long-term investments.

Save and save some more. It’s easy to dream about retirement, but if you intend to make those dreams a reality, start setting aside money now. If you have been saving for some time, make sure you are on track toward your end goal and weigh your ability to contribute even more. As you progress through your career, and your life, make sure to reassess your financial position and match your savings capacity with your goal. Try to increase your contributions as your financial circumstances allow, ideally by 1% each year.

Build your endurance. The old adage, “It’s a marathon, not a sprint” may sound cliché, but going the distance into a retirement that is financially secure will require planning and endurance. As you set your retirement goals, consider your current financial fitness and the discipline and actions it will take to help you get to the finish line within your ideal timeframe. Getting there does not happen overnight.

We’ve seen some evidence of that commitment during the pandemic. The CARES Act, the federal stimulus bill in response to the pandemic, gives more flexibility for individuals to take distributions or loans from their retirement plans without the usual penalties. Dipping into that savings can be tempting and understandable for anyone who has suffered an economic setback recently. But while many clients have requested the option to access their funds per the CARES Act rules, very few have taken full advantage since the law took effect in late March. It seems the peace of mind in knowing they can access their funds as needed has allowed them to consider the benefits of staying the course as much as possible. That trend seems to match what’s happening elsewhere too. In the aforementioned survey only 4% of respondents reported decreasing the amount they are saving because of the recent economic downturn, and more than 90% said they are moderately to extremely well prepared to weather the crisis. That’s the power of planning well.

Think about your overall financial wellness. Since you’re already focusing your energy on open enrollment decisions and retirement plans, why not examine other important financial considerations? We’ve seen more people looking to tackle financial decisions they had been avoiding, but that have taken on renewed importance in 2020. The pandemic has caused many people to pause and consider their overall financial stability and areas that need more attention. Now’s a good time, for example, to consider if you should invest in a life insurance policy or a plan for long-term care in your twilight years. Plan out other potential big investments you want to make, such as for your children’s college education or a long-term health savings plan. Covering all your bases now will increase the odds that you will grow your retirement account sufficiently to pay not just for the basics, but to support any activities you want to pursue after you leave the workforce, such as travel or charitable donations.

Reflect back and think ahead. It’s important to check back on your plan on a regular basis and determine if you are on track toward your goals. As the year wraps up, it’s a good time to check in with your financial professional and reflect on your successes in maintaining your savings discipline. Together you can consider the lessons that best inform your planning in the year ahead.

For most of us, the retirement finish line is too far in the distance to visualize clearly. But as we gather more knowledge and tools and maintain the right pace and discipline, we can improve our odds of finishing strong.

Jon Anderson is Head of Retirement at Cetera Financial Group in San Diego.

Kaci Skidgel is President of Retirement Plans at Summit Financial Group in Dallas.

About Cetera Financial Group®
Cetera Financial Group (Cetera) is a leading financial advice firm. It empowers the delivery of an Advice-Centric Experience® to individuals, families and businesses across the country through independent financial advisors as well as trusted tax professionals and banks and credit unions. It’s headquartered at 200 N. Pacific Coast Highway, Suite 1200 El Segundo, CA 90245-5670.

Comprehensive services include: wealth management solutions, retirement plan solutions, advisory services, practice management support, innovative technology, marketing guidance, regulatory support, and market research.

“Cetera Financial Group” refers to the network of independent retail firms encompassing, among others, Cetera Advisors LLC, Cetera Advisor Networks LLC, Cetera Investment Services LLC (marketed as Cetera Financial Institutions or Cetera Investors), Cetera Financial Specialists LLC, and First Allied Securities, Inc. All firms are members FINRA / SIPC.

Individuals affiliated with Cetera firms are either Registered Representatives who offer only brokerage services and receive transaction-based compensation (commissions), Investment Adviser Representatives who offer only investment advisory services and receive fees based on assets, or both Registered Representatives and Investment Adviser Representatives, who can offer both types of services.


Online more these days? 5 facts about entertainment news scams

2020-10-13T08:01:01

(BPT) – As Americans continue to follow stay-at-home and social distancing recommendations, their personal and professional online activity has drastically increased. As a result of the jump in online activity, the threat of data breaches and identity theft is greater than ever.

That’s because cybercriminals are getting smarter by continually adjusting their strategies to consumer behavior. After COVID-19 hit early this year, for example, they targeted their efforts even more closely to those spending the most work and leisure time on their smartphones, tablets, laptops and desktops. These days, many of their scams are aimed at people seeking free online entertainment — free movies and TV shows, breaking celebrity news or miscellaneous clickbait — as Americans often stay home rather than venturing into the pandemic-ridden world for recreation and amusement.

The risky side of entertainment news

How do the scammers get you? One way they ply their trade is to offer up tidbits of celebrity news and gossip or (supposedly) cost-free access to popular shows and movies, often through pop-up ads, emails or texts that show up while you’re working or playing online. When you click on the links presented, your device is quickly installed with malware that may allow criminals access to your personal information and log-in information.

“Cybercriminals use consumers’ fascination with celebrity culture to drive unsuspecting fans to malicious websites,” explains Baker Nanduru, VP of Consumer Endpoint Segment at antivirus software company McAfee. “As consumers increasingly spend more time online, it’s crucial that they stay vigilant about protecting their digital lives and a big part of that is being aware of and understanding the potential risks associated with their online activity.”

The good news? Forewarned is forearmed. Here are five facts that can help protect you and your family from such scams.

Everyone should view ads and news sites with a critical eye. The most savvy web surfers vet sources for credibility before clicking on ads for tabloid-like celebrity news or free-of-charge entertainment content. If the news sounds far-fetched or the offer seems too good to be true, it’s more than likely fake. The safest course of action is to visit credible news sites, wait for official entertainment releases and use only legitimate streaming platforms.

Con artists know pop culture. Be aware that certain celebrities are used as clickbait more than others, probably because their lives are of particular interest to the demographic groups being targeted. Interestingly, a McAfee study this year found the “most dangerous celebrity to search for” online this year to be actress Anna Kendrick. Other stars frequently used to lure people into online scams include Sean Combs (aka P. Diddy), Blake Lively, Jungkook, Mariah Carey, Justin Timberlake, Taylor Swift, Jimmy Kimmel, Julia Roberts and Kate McKinnon.

Cybersecurity software can help guard your privacy. A comprehensive security system like McAfee Total Protection offers another layer of heavy-duty protection against malware, phishing attacks and other nefarious threats in our increasingly online world. Further, McAfee’s WebAdvisor features can alert you to the latest scams by notifying you about malicious websites as they’re revealed.

You need to pay for what you use. It’s in your best interest to avoid downloading suspicious MP3s and to use legitimate music streaming platforms, even if they come at a cost. Why? These days, many illegal downloads are riddled with malware or adware disguised as MP3 files.

Parental control software helps protect your kids. Because children have their own celebrity favorites, it’s important that you set limits on their devices and use available controls to help minimize exposure to potentially malicious or inappropriate websites.

In a world of constantly evolving cyberthreats, it’s important to do everything you can to protect your family’s privacy and personal data. For more information about how to best guard your cybersecurity, talk to the experts at McAfee.


Pandemic Triggers Benefits Double Take at US Businesses

2020-10-08T07:01:00

(BPT) – On Jan. 1, 2020, the world welcomed the beginning of a new year with open arms. Little did we know of the challenges to come and the eagerness to leave 2020 in the dust.

While what lies ahead in the coming year is just as unknown, some experts say a return to normal, whatever that means, is not likely until November 2021 at the earliest.1 Many businesses are following state and local reopening guidelines and revising continuity plans accordingly — all while keeping operations on track, managing overhead, and doing their best to foster productive and satisfied employees.

A core component of a company’s bottom line and employee satisfaction is the benefits package offered to employees. Many businesses decided on their offerings prior to COVID-19’s impact and without consideration for its global effects. Yet, among employers and their workers, the pandemic has created a renewed awareness about health coverage.

A study by worldwide research, consulting and professional development organization LIMRA notes that 40% of employers say the pandemic has altered their views on the importance of the benefits they offer, almost universally shifting toward a view of benefits as more important now.2 This altered perception on benefits is leading employers to reconsider their offerings this open enrollment season. “Stronger on the Other Side,” a white paper from supplemental insurer Aflac, recently analyzed these changes, highlighting the opportunity business owners have to update their current benefits packages in light of the physical and emotional effects of the coronavirus.

Prepare for unexpected health complications

Some symptoms of COVID-19 are distinguishable and tend to linger, including fever, cough, lost sense of taste and smell, fatigue and shortness of breath. A recent CDC report indicated that 35% of patients who tested positive for COVID-19 had not returned to their typical state of health after two to three weeks after testing.3 This can result in chronic conditions like pneumonia, heart attack, kidney damage and more, significantly increasing the length — and expense — of recovery.

“COVID-19 appears to affect everyone differently and is indiscriminate. From healthy 20-somethings to people with more common comorbidities like high blood pressure, asthma and diabetes, it is unknown who is likely to have long-term consequences,” says Stephanie Shields, senior vice president of Broker Sales at Aflac. “Because of the pandemic, people who may have typically overlooked benefits options outside of their health insurance in the past are likely reevaluating the value of supplemental insurance plans such as hospital indemnity and critical illness.”

This increased interest in supplemental coverage is in line with a lack of confidence in the coverage offered by health insurance. Aflac’s annual WorkForces Report found that 33% of employees either do not feel confident or are unsure if their health benefits will protect them or their family in the event they are affected by COVID-19.4

“Our survey shows that a benefits package that includes supplemental insurance and telemedicine options may help boost this confidence level and overall satisfaction,” Shields added.

Getting help with emotional burdens

In addition to the physical effects of the coronavirus, loneliness, stress and fear are also taking a toll on the emotional health of Americans. Extended disruptions in daily routines and social distancing requirements are increasing concern about people’s well-being, with 53% of adults reporting their mental health has been negatively impacted due to worry and stress over the coronavirus.5

“It is easy to see a company’s benefits package as merely insurance options covering medical costs, but it involves more than health insurance alone,” Shields added. “Don’t underestimate the value of services such as an employee assistance program, health advocacy services, wellness programs and financial support services. These give access to specialists who can help with things like work/life issues, medical bill negotiation and explanation, how to stay healthy at a time of remote work, and budgeting counselors.”

As the workforce continues to adapt to changes brought on by the pandemic, employers have learned how to pivot. Understanding the emotional and physical effects of the virus and the benefits options available, businesses can take strides during open enrollment to ensure that when 2020 is finally over, their employees can emerge stronger on the other side in 2021 and beyond.

1 “A return to ‘normal’: How long will the pandemic last?” Medical Press. Accessed Sept. 30, 2020. https://medicalxpress.com/news/2020-07-pandemic.html.

2 “Will Employers Make Changes to Workplace Benefits Due to COVID-19?” LIMRA. Accessed Sept. 30, 2020. https://www.limra.com/globalassets/limra/research/research-abstracts/2020/impact-of-covid-19-on-employers-approaches-to-workplace-benefits/2020_insurancebenefitchanges_infographic.pdf.

3 “Symptom Duration and Risk Factors for Delayed Return to Usual Health Among Outpatients with COVID-19 in a Multistate Health Care Systems Network.” Centers for Disease Control and Prevention. Accessed Sept. 30, 2020. https://www.cdc.gov/mmwr/volumes/69/wr/mm6930e1.htm.

4 The 2020-2021 Aflac WorkForces Report is the 10th annual study examining benefits trends and attitudes. The surveys, conducted by Kantar, captured responses from 1,200 employers and 2,000 employees across the United States in various industries. Learn more at Aflac.com/AWR.

5 “The Implications of COVID-19 for Mental Health and Substance Use.” KFF. Accessed Sept. 30, 2020. https://www.kff.org/coronavirus-covid-19/issue-brief/the-implications-of-covid-19-for-mental-health-and-substance-use.

The content within is for informational purposes for broker-facing audiences. This information is not approved to distribute to prospective insureds, or to use as a solicitation. Misrepresenting this, or any, information to solicit or induce an insured to lapse, forfeit, or surrender an insurance policy is prohibited by law. Any use not specifically permitted herein is strictly prohibited. Aflac includes Aflac and/or Aflac New York and/or Continental American Insurance Company and/or Continental American Life Insurance Company.

Z200690 EXP 10/21


Budget-friendly tips for a safe and joyous holiday 2020

2020-10-08T08:01:00

(BPT) – Uncertainty continues into the 2020 holiday season, with limited travel, canceled events and strict budgets changing how Americans will celebrate this year. According to a recent Coinstar Holiday Survey, the majority of Americans said COVID-19 will influence how they celebrate the holidays.

Fortunately, by thinking outside the box and keeping a positive attitude, you can stay healthy, stretch funds and create merry moments. Let these tips inspire you to celebrate the holiday season safely and on budget:

Maintain traditions in new, safe ways

Traditions bring comfort and hope, so rather than forgoing beloved activities due to coronavirus concerns, get creative instead. Plan a car caravan to look at holiday lights and have everyone keep a scorecard of favorite houses including winners for most creative, brightest, funniest and overall best. Set up a video chat and bake favorite holiday treats in real time from afar. Relatives can virtually tuck kids into bed by reading classic holiday books through a free digital video platform. These activities are safer to enjoy and will create meaningful memories to make the season special.

Make gifts to save money

You can still have a wonderful holiday even on a tight budget. A budget-friendly option is to make it a homemade holiday this year. Face masks and hand sanitizer are great stocking stuffers that you can make and will be appreciated, especially this year. Patterns are readily available to make face masks and you can find recipes online for creating custom hand sanitizer. Another idea is to choose all handmade gifts from Etsy or local artists in your area, so you can give unique presents while supporting small businesses.

Cash in spare change

Even with fewer in-person gatherings and reduced gift giving this season, most people have increased expenses during the holiday season. Cashing in spare change is a good way to stretch your budget. Research shows Americans with spare change at home estimate that they have on average $113 in and around their homes. These funds can be used to buy gifts or apply to other holiday expenses. Coinstar kiosks found at most grocery stores are an easy way to convert loose change for cash, a no-fee eGift card or tax-deductible charity donation.

Plan a virtual gift exchange

According to the Coinstar Holiday Survey, two in five Americans who say their holiday will be different due to COVID-19 say they do not plan to travel or attend in-person gatherings. To enjoy the holidays safely, consider a virtual gift exchange with friends or family. Drop off or mail gifts and plan a time for everyone to video chat and open presents together. Get dressed in your favorite holiday attire to make the event feel special, whether that’s festive formal wear or ugly sweaters and sweats. Then, take turns opening gifts and feel the joy.

Give gifts with meaning

Rather than a traditional present, consider alternative gifts that show you care. Do you have a talent that would benefit others, such as tutoring a friend’s child who is studying remotely? Could you drop off a meal for a senior who’s homebound? Could you donate a snack basket for hard-working delivery personnel? Lastly, instead of a present, you could make a donation in the recipient’s name to a charity close to that person’s heart.

Delay holiday celebrations

All of these ideas can help you maximize the holiday season, but if you still long to celebrate in person, consider planning a gathering for later in 2021. According the survey, about half said they would consider “Christmas in July” in 2021 for in-person celebrations. So, whether it’s a summer Christmas event, an early Friendsgiving or another winter holiday, it’s something to look forward to once it’s safe again. Send out “save the date” invitations and put your creative juices to work for a summer get-together.


3 focus areas to get your finances back on track

2020-10-06T08:01:00

(BPT) – The COVID-19 pandemic has hit many people hard financially. From furloughs to job loss and from strict budgets to depleted savings and much more, people are making adjustments as needed. It’s important to stay focused on your financial well-being and take simple steps so you can recover and thrive in the future.

“Many people who have experienced financial disruption need some help to get their savings back on track,” says Andy Harmening, Consumer and Business Banking director at Huntington. “Even in a strong economy, managing everyday finances can be stressful. Fortunately, with a little diligence and some digital tools that make it easier to save, people can find the financial peace of mind they’re looking for.”

Harmening says it is possible to improve your finances in a post-COVID world by focusing on three key areas:

Create an updated, agile budget

Your income may change, so it’s important to understand your spending habits and create a realistic budget. Track all your spending for a month and separate out necessities versus nice-to-have items. You can also input your income and expenses and let an online budget calculator do the math.

Keep in mind variables due to the pandemic that may impact your budget. For example, a shorter work week, lower gas prices, more money on groceries and perhaps less money eating out. You’ll want to incorporate these positive and negative changes, and if possible, leave some wiggle room for future changes. Additionally, some things like gym memberships and parking passes may have paused when the pandemic started but are now being charged again. Sophisticated online banking solutions, such as a spend analysis tool, can give you an eye-opening look into how your spending adds up so you can make smart adjustments.

Replenish emergency funds with smart tools

Many people have tapped or even drained their savings to make ends meet as the pandemic hit. By updating your budget and getting ahead of spending, you can start to replenish emergency funds. Saving even a small amount regularly can help create an emergency fund that will put you in a better position to handle the potential of future financial challenges.

Small amounts over time — even just $5 — can add up to a robust emergency fund that provides peace of mind. Money Scout by Huntington is a new tool customers can enroll in that analyzes spending habits, income, and upcoming expenses and finds money you’re not using in your checking account. Then, it moves that money, from $5 to $50, automatically to your savings, up to three times a week. Bit by bit, it will help you build savings.

Automate bills and pay down debt

To keep your credit healthy, take steps to pay your bills on time and start reducing debt. A good first step is to automate wherever possible. Direct deposits and automatic bill payments ensure nothing gets overlooked or falls through the cracks in spending and saving.

If you’ve leaned on your credit cards during the pandemic, pay down the debt with the larger interest rate first to avoid wasting dollars on paying interest, even if that means paying smaller debts first. This will help you save money in the long run.

Keep in mind, it can be tempting to tap into money set aside in a retirement plan to cover expenses, but even if that can be done without a penalty, it can rob you of potential financial security down the road. If you need to pause contributing to a retirement plan temporarily to get finances back on track, that’s OK. But avoid borrowing from these accounts and start contributing to them as soon as you’re able to set yourself up for a bright financial future.


New ways to save more with your FSA or HSA

2020-10-01T07:01:01

(BPT) – If you currently have a flexible spending arrangement (FSA) or a health savings account (HSA) through your employer, you probably appreciate knowing that you have some pre-tax savings stashed away in case you need them for a healthcare expense. FSAs and HSAs aim to provide convenient, affordable spending options, allowing employees to create accounts where they can deposit pre-tax funds during each pay period to cover out-of-pocket healthcare expenses.

New this year, you can use those funds to help pay for over-the-counter (OTC) medicines (without a prescription) and menstrual or feminine care products. The expanded eligibility to include these expenses was part of the Coronavirus Aid, Relief, and Economic Securities (CARES) Act passed in March 2020.

FSAs and HSAs can help reduce costs — if you use them

Unexpected healthcare costs can put a serious dent in your budget. And if you have healthcare expenses — whether you anticipate them or not — having an FSA or HSA can save you a lot. Americans with employer-sponsored insurance are increasingly funding more of their own healthcare expenses. On average, workers paid $6,015 for family coverage and $1,242 for single coverage in 2019, according to the KFF Employer Health Benefits Survey.

However, chances are good that you still have funds in these accounts that you haven’t yet been able to use this year. In fact, most FSAs work on a “use it or lose it” basis, resulting in over $400 million per year going unspent by employees. This new eligibility for coverage of OTC medicines (not requiring a prescription) and menstrual care products (including tampons, pads, cups and other products) provides consumers with even more options to spend these tax-free funds, which is good news for anyone trying to save on costs.

The other good news is that the law is retroactive, so if you still have receipts for any purchases of OTC medicines or menstrual care products from as far back as Jan. 1, 2020, you may be eligible to receive reimbursement of those funds by submitting the necessary paperwork to your FSA/HSA administrator.

Newly eligible products

OTC medicines offer safe, effective relief for a wide variety of symptoms and conditions, providing the first line of defense for families’ healthcare needs. In previous years, a prescription was needed to use FSA or HSA funds for these everyday products. Keep in mind, however, that OTC medicines should not be considered a substitute for consulting your healthcare provider, especially if you or a family member has concerning symptoms, such as any known coronavirus symptoms.

Menstrual products also provide necessary comfort and care for women, and add up to a surprisingly large expense. U.S. women altogether spend $3 billion per year on menstrual care products, according to the National Center for Health Research. BenefitsPro.com also reports that women spend around $4,752 on tampons and pads throughout their lifetime, which doesn’t account for other menstrual health-related products they also use.

All of these products add up to a lot of additional costs. And during a time when more than 9 in 10 Americans feel anxious about finances amid the COVID-19 pandemic — with healthcare bills being one of the top 10 stressors, according to the National Endowment for Financial Education — finding new ways to save money helps relieve some of that stress.

Have questions, or don’t know if you or your particular expenses are eligible under your plan’s coverage? Contact your employer’s FSA/HSA administrator with questions about your eligibility and the eligibility of specific products, and visit TaxFreeOTC.org to learn more.


Make These 5 Steps Toward Financial Wellness This Fall

2020-10-01T07:01:01

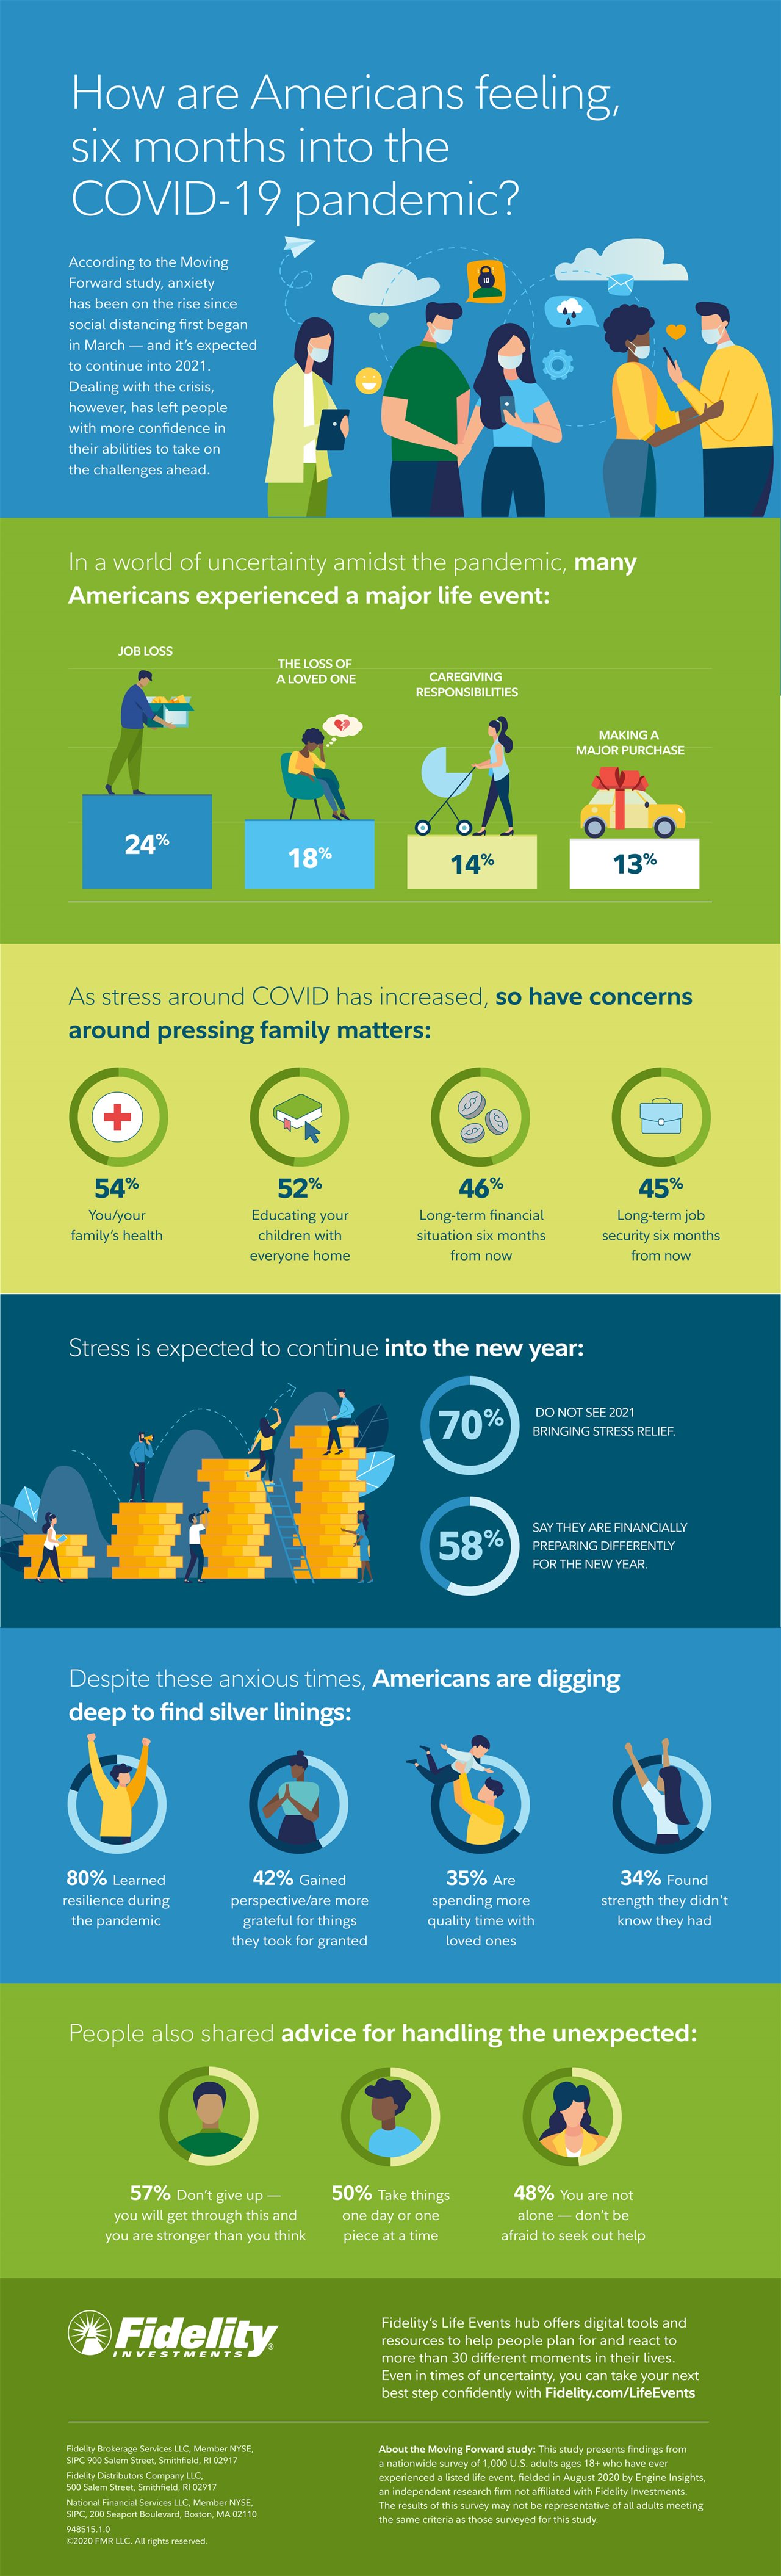
(BPT) – October is National Financial Planning Month, a time when we traditionally slow down, check in and make some progress toward our long-term financial goals. Big-picture money objectives may feel difficult right now, while we grapple with the economic fallout from the pandemic and struggle to meet immediate financial needs. Nearly half of Americans are worried about their financial future, according to Prudential’s 2020 Financial Wellness Census, and most people perceive their financial mobility as fixed.

In this current climate, it’s important to take stock of our new reality, adjust our strategies and move toward practicing financial wellness, even if financial security feels temporarily out of reach. Amanda Clayman, financial therapist and Prudential’s Financial Wellness Advocate, is here to guide us through some steps for looking to the future with hope:

1) Make Time for Your Money: You cannot plan for the future if you do not know where you are now. Setting consistent times and days to sit down and look at your statements, bills and paychecks goes a long way in feeling confident about your financial ability — no matter how much is in the bank. The more you familiarize yourself with your situation, the less scary it all becomes.

2) Focus On What You Can Control: Uncertainty is more prevalent than ever during the pandemic. Variables like employment stability and stimulus checks can leave us feeling stressed. As much as you can, let go of what lies outside your control. Instead turn your energy toward the activities where your efforts make an impact, like reallocating your savings and reevaluating your expenses.

3) Tune In To Your Feelings: Emotions about money can be messy. Anxiety, insecurity or fear can cause us to react disproportionately to financial situations, often prompting us to extremely restrict or overspend. Begin Financial Planning Month by examining your emotional state these days and identifying how your feelings may influence your decision-making ability.

4) Look to Your Community: Those of us who formerly prided ourselves on being self-sufficient are turning to our communities, neighbors and families for support — emotionally and financially. This can be hard to come to terms with, but also has the power to draw us closer together and create a future in which we take care of each other. Now is the time to put shame on the shelf and learn about the community resources at our disposal.

5) Make an Adaptable Plan: Looking long-term might be daunting right now. Make the best plans you can with the information available to you now, and expect to change them as your situation evolves. Remember, you are adaptable and capable of responding to adversity. These plans do not need to be set in stone, but having them in place will help you feel proactive and hopeful about your financial future.