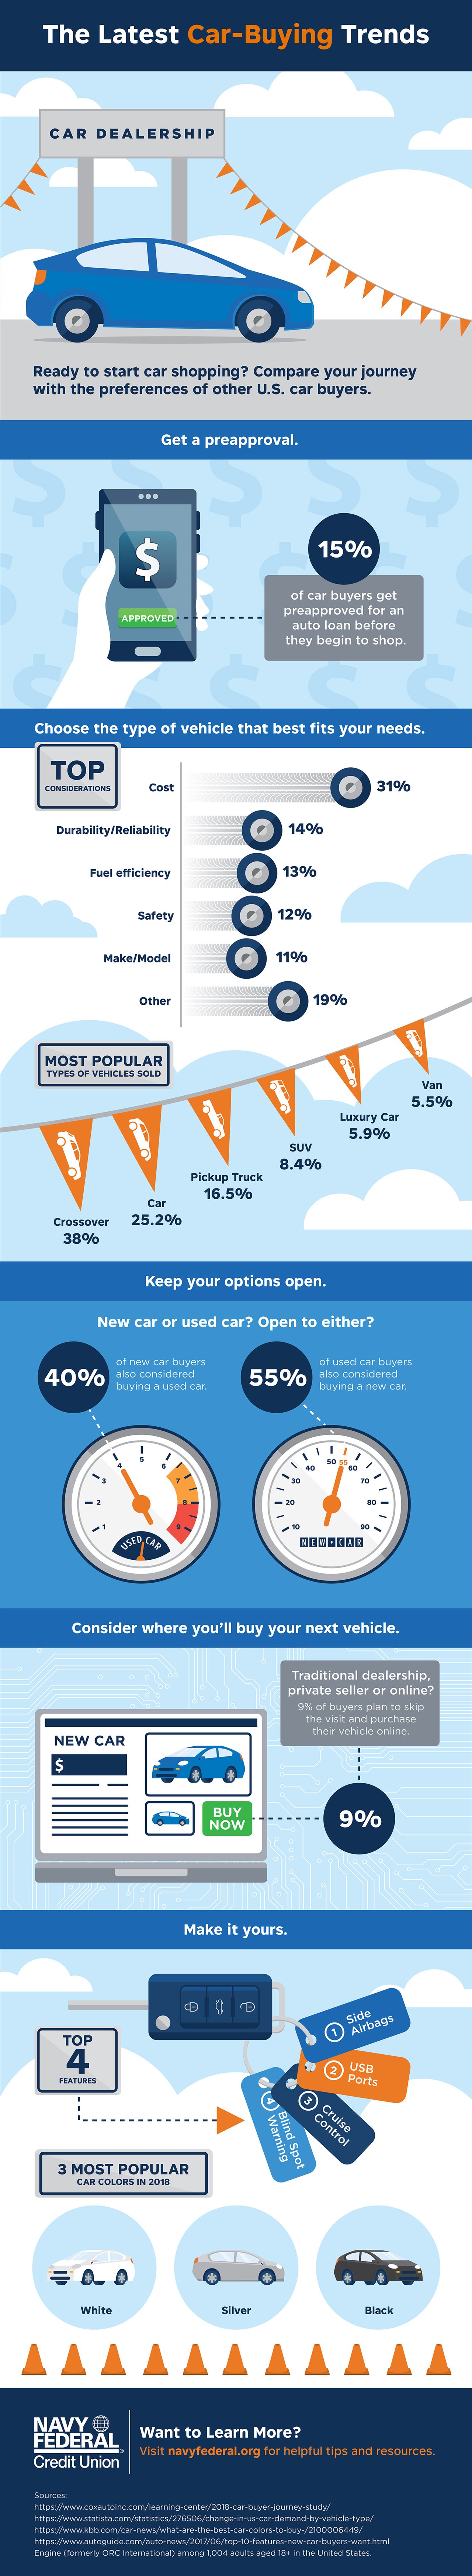
Ready for a new car? Here’s how to find the best fit [Infographic]

2019-09-04T08:01:00

(BPT) – Choosing the right car can be exciting and daunting. To ensure you get the best deal on the best car for your needs, you’ll want to take time to establish what you’re looking for in a car before you start shopping. Many financial institutions, such as Navy Federal Credit Union, offer expert advice along with financing options. As you search for your ideal car, it pays to do your homework and compare all your options.


What companies can do to adapt to rapid change

2019-09-04T06:01:00

(BPT) – In this era of rapid change, companies need agility to meet customer needs — and to survive. Agility refers to a company’s ability to respond quickly to challenges like new technology, competition, changing needs of consumers and sudden shifts in the business environment.

A truly agile company doesn’t just react to change, but proactively seeks new information and embraces change in a collaborative way. An agile organization anticipates and makes the most of change, acting quickly to meet the rapidly evolving needs of customers and the marketplace.

How can organizations become more agile? Director of research and thought leadership for Dale Carnegie and Associates Mark Marone, Ph.D., said, “It takes more than smart people and good data to become agile. Along with good tools and processes, it takes the right combination of resilience, social intelligence and capacity for action, aligned with clear organizational purpose, to create a strong foundation for agility.”

Success in the face of change relies on the agility of companies, and that agility must be nurtured and supported from the top down, with these factors in mind:

Develop a customer-focused purpose

A recent Dale Carnegie study found corporations that performed best in the face of rapid change had a strong customer focus. When employees maintain a strong focus on customer needs, it empowers them to suggest and advocate for changes that make the organization more responsive in providing value for customers.

Foster communication

While it’s crucial to communicate clearly to the organization about its goals and concerns, leadership also needs to listen. Being open to the suggestions and questions of all employees results in the ability to respond more quickly to change.

Encourage resilience

Because agility requires making rapid decisions, some risk is involved. Encouraging a culture that tolerates the occasional misstep and promotes learning from mistakes helps create resilience. Dale Carnegie said that resilience means being able to “develop success from failures. Discouragement and failure are two of the surest stepping stones to success.” Learning from failure is the best way to become more adept in handling fast-paced change.

Build self-confidence

Allowing employees to share ideas and learn from missteps helps instill confidence that they have something to contribute, and that they can be relied on to adapt to change. Modeling self-confidence is insufficient — it’s important to show employees you have confidence in them. Self-confidence encourages employees to experiment and explore new solutions. Senior leaders set the tone, but mid-level and frontline leaders are also in a good position to increase self-confidence in their teams.

Promote positivity

People with a positive outlook expect and get positive outcomes more often than those without it. Positivity enhances problem-solving and decision-making, helping people think more flexibly, innovatively and creatively.

Instill trust

Communicating honestly and following through on expectations helps instill trust, which creates an environment of psychological safety. Knowing leadership will support risk-taking and not blame employees for missteps is key. According to Dale Carnegie, principle number one is, “Don’t criticize, condemn or complain.” Helping employees learn from failures without penalizing them creates an atmosphere where employees are willing to express ideas and opinions, rather than being paralyzed by fear of negative feedback.

Develop effective tools and processes

Provide employees with tools and processes to handle new technologies, changes in workplace methods and shifts in customer needs. In a Dale Carnegie survey of employees concerned about losing their jobs to AI, 68% of respondents said getting additional training would be very or extremely important to retaining their positions. Most employees look to their employers to provide that training.

Enhance capacity for action

Supporting collaboration and creative intelligence helps drive innovation and positive action. Insights and action plans can be derived from cross-functional teams as well as a corporate culture of information-sharing and encouraging creative thinking.

“Involving employees in initiating ideas for change is key to agility,” said Marone, adding, “Those closest to the needs of customers are in the best position to identify problems and generate solutions.” And employees who have helped develop solutions in the face of change will be their strongest advocates.

To learn how Dale Carnegie Training can help you strengthen foundations of agility in your people and organization, visit DaleCarnegie.com.


Planning to retire on your 65th birthday? We didn’t think so

2019-08-31T08:29:00

(BPT) – The traditional notion of retirement — a switch from full-time work to full-time leisure — is becoming a thing of the past for millions of Americans. In fact, according to a recent UnitedHealthcare survey (conducted by Wakefield Research on behalf of UnitedHealthcare) of 1,000 nationally representative Americans 62 and older, 24% of those who did retire chose to re-enter the workforce.

Delaying retirement or returning to work may influence your Medicare decisions. Here are some points to keep in mind if you plan to continue working past your 65th birthday or return to work.

Why enroll in Medicare at 65?

Timing matters when it comes to signing up for Medicare. If you’re about to turn 65, you have a seven-month window called an Initial Enrollment Period (IEP). That includes the month of your birthday, the three months before and the three months after.

If your 65th birthday is on June 15, your IEP starts March 1 and ends Sept. 30.

If you don’t have health insurance through your employer, your IEP is the time to figure out which Medicare coverage would work best for you.

If you have coverage through your employer and plan to keep working, check with your HR department or benefits administrator to see how Medicare might work with your employer coverage. Many sign up for Medicare Part A at age 65 either way since most get it without paying a monthly premium.

How Social Security benefits can affect your Medicare enrollment

If you already receive Social Security benefits when you turn 65, you’ll be automatically enrolled in Original Medicare (Parts A and B), and your Medicare card will arrive before your 65th birthday.

Your Part B premium will be automatically deducted from your Social Security payments. If you don’t want Medicare Part B, notify Medicare to opt out.

Many wait to claim Social Security until their 66th birthday or later to increase their monthly payments. If you fall into this group but still want Medicare coverage when you turn 65, it’s up to you to enroll because it won’t happen automatically.

Penalties for delaying Medicare enrollment

If you’re planning to work beyond 65, you may be able to wait until you retire to enroll in Medicare. For many, that’s the right choice, as their employer coverage is more robust. But consider your prescription drug coverage, and when you’re ready to retire, be aware of the enrollment windows to avoid penalties.

If your employer plan doesn’t offer prescription drug coverage, or if the coverage isn’t as good as Medicare, consider enrolling in a Medicare Part D prescription drug plan. That’s because Medicare imposes a permanent late enrollment penalty that will increase your monthly premium if you later decide to sign up for a Part D plan. You must be enrolled in Part A and/or Part B of Medicare before you can enroll in Part D.

When you retire or lose your employer coverage, you’ll be eligible for a Special Enrollment Period (SEP). You can enroll in Parts A and/or B for up to eight months after the month you retire or your employer health plan coverage ends, whichever comes first. But if you delay beyond eight months, you could pay more for your Part B premium — for as long as you have Part B.

For each year you delay enrollment in Part B, an extra 10% is added to your premium.

Want Medicare Advantage or Part D when you retire? Your enrollment window is shorter.

When people sign up for Medicare, many also choose to enroll in a private Medicare plan — either a Part D plan or a Medicare Advantage plan (Part C).

Many Medicare Advantage plans provide additional benefits beyond those of Original Medicare (Parts A and B), such as dental, hearing and vision coverage. Most plans also bundle in prescription drug coverage and fitness or gym programs.

But the window to sign up for these plans is shorter than for Part B — only two months. To avoid a lapse in coverage, time your enrollment accordingly.

Bottom line

Just because you delay your retirement doesn’t mean you should delay your Medicare enrollment. Talk to your HR or benefits coordinator at work to get personalized advice based on your needs.

Visit Medicare.gov or www.ssa.gov for more information.

You can find additional resources on MedicareMadeClear.com.


Is your small business throwing money away because of outdated PCs?

2019-08-27T11:53:01

(BPT) – If you’re running a small business, chances are your budget is tight. You may consider buying new PCs a luxury you can’t afford, at least not right now. But if your employees are working on computers that are five years old or older, this could actually be costing you serious money.

How do older computers result in your business throwing money away?

1. Lost employee productivity

Older computers result in less productive employees, for a variety of reasons. In a recent study of 3,297 small businesses in 16 countries by J. Gold, commissioned by Intel, the small businesses reported that employees using older PCs spent what could amount to 11 hours per year just waiting for their computers to start up.1

And that’s just one of the ways employees are slowed down. Anyone trying to use new or resource-intensive software applications, load web pages or run a number of applications at the same time on an old computer knows it can result in massive slowdowns. Computers with slower, less powerful processors typically can’t handle the load.

When work doesn’t get done in a timely manner due to these slowdowns, business owners can mistakenly think they need to hire more employees to handle the work, which will likely cost more money. Or they may turn to cloud computing or software as a service (SaaS) to try to boost efficiency and save money. However, while technologies such as cloud computing and SaaS may help somewhat, to make a substantial difference they would also require the speed and processing power not available from your old computers — asking more than an older machine can deliver.

Overall, the J. Gold study found that computers five years old (or older) can result in lost productivity, up to 29%. What does that mean in terms of dollars? Each older PC being used in your business could cost you up to $17,000 annually in lost productivity alone.2

2. Computer malfunctions and upgrades

On top of lost productivity due to slower start-up times and inefficiently running software applications, PCs that are five years old or older may be more likely to break down or need upgrades to function properly. While it may seem more cost-efficient just to install more memory here, make a repair there — the money you’re dumping into outdated computers adds up. And that’s money you could have used to invest in new PCs.

The J. Gold study discovered that over the course of a year, the small businesses that they surveyed estimated about 43% of their older PCs malfunctioned or suffered a breakdown. The study also found that the reported repair costs for PCs five years old or older are $662 per year, on average.3 Enough of such repairs could soon equal the cost of a better, more powerful new PC — and newer PCs are less likely to fail or malfunction.

3. Cybersecurity breaches

The last thing a small business wants is to have to cope with a cyberattack, whether that means being hacked or getting hit by malware, but it can and does happen. A survey by global insurance company Hiscox reported that 47% of small businesses experienced at least one cyberattack over the span of a year, and nearly half of those businesses had been hit more than once.4 Unfortunately, the older your PC, the more vulnerable it may be to cyberattacks. In the study by J. Gold, the respondents estimated that nearly 35% of their PCs over five years old had been hit with malware or some other form of cyberattack, while less than 6% of their PCs under one year old had been attacked.

A data breach can be extremely costly for a small business, beyond the harm to your customers and to the reputation of your business. In the Hiscox survey, small businesses estimated that the average cost of cyber incidents over the past year totaled $35,604.5

Updating your PCs to the newest operating system available (currently Windows 10*) is often the best way to boost your cybersecurity. However, running Windows 10 on an older computer means you may not have access to all the newest security features. If you continue to run an older operating system like Windows 7, you should know that Microsoft will not be providing security features for Windows 7 after Jan. 14, 2020.

What’s the upshot? Consider the potential cost in terms of lost employee productivity, repairs and security risks when you calculate the price of new computers for your business. If your company’s PCs are five years old or older, it may not be saving you money to hang on to them — it could be costing quite a lot. Look for PCs that run 8th Gen Intel® Core™i5 or Core i7 processors, which help computers access information more quickly, helping to deliver reliable and efficient performance to enable your employees to work more effectively and productively. Upgrading to newer, more powerful computers can be the best investment you can make in your business.

1 2018 web-based study commissioned by Intel and conducted by J. Gold Associates, LLC.
2 Also based on the 2018 web-based study commissioned by Intel and conducted by J. Gold Associates, LLC. 3,297 respondents from small business in 16 countries (Australia, Canada, China, France, Germany, India, Italy, Japan, Mexico, Saudi Arabia, South Africa, Spain, Turkey, UAE, UK, USA) estimated that for PCs over five years old, employees would be up to 29% less productive, based on an average assumed employee’s salary of US$60,000, so that the lost productivity cost would amount to US$17,000. To review this statistic and the full report, see https://www.intel.com/content/www/us/en/business/small-business/sme-pc-study.html.
3 The percentage of malfunctioning computers is based on based on a 2018 web-based survey, commissioned by Intel and conducted by J. Gold Associates, LLC., of 3,297 respondents from small business in 16 countries (Australia, Canada, China, France, Germany, India, Italy, Japan, Mexico, Saudi Arabia, South Africa, Spain, Turkey, UAE, UK, USA) to assess the challenges and costs associated with using older PCs.
4 The 2018 Hiscox Small Business Cyber Risk ReportTM commissioned Forrester Consulting to assess the organization’s cyber readiness.
5 Ibid.
*Intel, the Intel logo and Intel Core are trademarks of Intel Corporation or its subsidiaries in the United States and/or other countries.


Significant student benefits of flexible classroom seating

2019-08-27T08:01:00

(BPT) – Have you seen a modern classroom with a variety of seating options that allow kids to sit, stand, wiggle and wobble as they engage in learning throughout the day?

If so, you are familiar with flexible seating, a leading educational trend in K-12 classrooms nationwide. Both teachers and students are finding this alternative to traditional rows of desks to better align with how kids move, learn and collaborate. This in turn helps teachers engage and educate students.

Wondering how flexible seating could help at your local schools? Here are the top benefits of flexible seating from the educational experts at Smith System:

Choice

Students feel empowered by having some degree of choice and control over their environment. Flexible seating allows students to choose where they work and with whom. It also allows them to change their location and positions as needed, which teachers believe supports the development of higher-order thinking skills.

Physical health

Flexible seating allows children to wobble, rock, bounce, lean or stand, which increases oxygen flow to the brain, blood flow and core strength. Physical activity is linked to higher academic performance, better health and improved behavior. An academic paper by Matthew T. Mahar titled “Effects of a Classroom-Based Program on Physical Activity and On-Task Behavior,” found that simple in-class activities can boost performance. Studies suggest that children who participate in short bursts of physical activity within the classroom have more on-task behavior, too.

Comfort

An uncomfortable student is a distracted and unproductive student. For example, picture a student who skipped or didn’t have access to breakfast. As the countdown to lunch approaches, his or her growling stomach will make it impossible to concentrate on the teacher’s voice. An uncomfortable chair can have the same effect. Flexible seating encourages students to find their best spot to stay calm, focused and productive.

Community

Traditional desks can make students territorial or possessive over their space and supplies. Flexible seating encourages students to share both seating spaces and supplies needed to complete educational tasks. Plus, it encourages them to take turns in different locations and with different seating options.

Collaboration

Flexible seating allows students to quickly and easily pair up, work in small groups or discuss educational topics as a whole class — without moving numerous heavy desks to establish eye contact. This encourages communication and collaboration to boost critical thinking and deeper understanding of educational materials.

Participation

A 2012 study from the University of Minnesota found that students participated 48% more in discussions in a classroom with collaborative group seating versus traditional lecture-style seating, and also improved their performance on standardized tests. This underscores the value of flexible seating and its ability to create a collaborative environment that boosts participation.

Communication

When introducing flexible seating, teachers must establish new classroom management tools. That includes creating a system to make seating choice fair and nondisruptive. It also requires introducing higher-order thinking skills, like problem-solving, and emotional skills, like conflict resolution. There’s also much value in fostering turn-taking and patience, especially for a generation of kids immersed in immediate gratification.

Sensory input

Many flexible seating options stimulate students’ sense of touch. This type of stimulation can help children focus and process information. Sensory input is especially helpful for students with ADHD, ADD and ASD.

Fun

Flexible seating helps make learning fun. Children look forward to where they will sit, and each day becomes a unique educational adventure. Teachers adopting a change to flexible seating can set a positive mindset that is infectious to students.

Flexible seating helps students become more enthusiastic learners while giving them choices, which is empowering. To learn more about flexible seating, visit smithsystem.com.


5 steps you can take today to get closer to a secure retirement

2019-08-23T08:11:22

(BPT) – Did you know nearly 1 in 3 people think they’re more likely to learn Bigfoot is real than to save enough to retire comfortably? That’s according to a recent survey from AARP and the Ad Council.

But successfully saving for retirement doesn’t have to be a fantasy — or scary. Chances are you’re better at saving than you think. Have you put kids through college? Bought a house? Purchased a car or two? You’re probably better at achieving financial goals than you give yourself credit for. The careful planning and savings skills you’ve already used can help you reach your next big financial goal: a secure retirement.

The right tools make it easier. You can get started today with a free online resource from AARP where you can create your personal action plan in just a few minutes. Meet your friendly digital retirement coach, Avo, at AceYourRetirement.org.

“In just three minutes you can get answers to a few simple questions, plus personalized tips and saving strategies,” said Debra Whitman, AARP executive vice president and chief public policy officer. “The to-do list format is effective and works for any age.”

The sooner you start, the sooner you’ll have peace of mind, and a concrete plan. While everyone’s situation is unique, here are steps you can take today.

1. Take advantage of your employer’s retirement benefits. If your workplace offers a 401(k) or another savings plan, make sure you’re getting the most bang for your buck. If your employer matches part of your contribution, aim to contribute at least enough to get the full match.

“It’s basically free money for your future, and it can be a huge way to amplify the amount you’re able to save for yourself,” said Whitman.

If possible, consider boosting your contribution past that employer match by a percentage or two, to increase your savings even more. A long-term goal might be to set aside 10-15% of your income as a contribution to your 401(k).

2. Try to pay down debt. No matter your situation, reducing debt is always smart, as debt you carry eats away at savings you’re trying to set aside. Check interest rates on your current mortgages, car loans, home equity loans, parent loans or credit cards. Consider working toward paying down loans or cards with the highest interest rates first. Call your credit card companies and ask for a lower interest rate. Some debt may be eligible for refinancing, so consider that option to lower interest rates.

3. Have a family conversation. When it comes to any big financial decision, it helps if everyone is on the same page. You and your spouse could create a budget and incremental goals to work on together. Talk to your adult children about how paying down your debt and saving for retirement is a priority, and that helping them with their education, housing or other responsibilities is a secondary goal.

4. Plan your retirement timing. “As soon as possible” isn’t the best way to decide when to retire. If your health and work situation allow, delaying retirement until your late 60s or even early 70s can make a big difference to your long-term financial security.

“Earning a few more years of income can really help you grow your nest egg and waiting to claim Social Security increases your annual benefit for the rest of your life,” said Whitman.

Calculate your Social Security benefits to determine your best strategy at ssa.gov/benefits/retirement/estimator.html.

5. Live within your means. Spending only what you can afford is key to financial security. The sooner you develop a budget and track your spending, the more cash you’ll save in the short term, helping you make more accurate projections for the long term. Enjoy life now, but don’t let that enjoyment come at the cost of your future. Saving money consistently every month can help make a secure retirement a reality.

These goals are within your control, and you can make progress if you start small, start today and plan. For more information, visit AceYourRetirement.org.


Searching for a deal on a family wireless plan? Here’s what you should know

2019-08-19T08:01:00

(BPT) – Sharing your wireless plan with family members is a great way to save. It eliminates the hassle of multiple bills and lets you benefit from bundled savings offered by your provider. But choosing the right one requires some homework: Family plans today come in all shapes and sizes.

Here are a few key things to consider before signing your family up with a new carrier.

How much data do you need?

The biggest difference in wireless plans these days is based on your data needs. Since cellphones function more as personal computers than calling devices, data packages drive up the price far more than minutes or texts.

Many carriers offer “unlimited” data which, at a glance, may seem like a great option for a family. But unlimited data plans actually have some limits. Most carriers give you some super-fast LTE data but then slow down your speeds after you’ve used a certain amount.

Instead, calculate your actual data usage to see if you can adopt a plan that is more affordable. By connecting to Wi-Fi and using other data saving methods, the average person uses less than 3GB of data per month. Once you’re clear on your real data usage, you can choose a more customized plan, and the savings can be substantial.

Do you really need the latest phone?

Before you settle on a family plan, consider what you’re going to do regarding cellphones. There are plenty of choices available from a new carrier, but purchasing a few new phones, or even one, can be an expensive proposition.

Most wireless carriers allow you to bring your own device to their service, if the phone is compatible with their networks. Some carriers will even attempt to entice new customers with “Bring Your Own Phone” incentives, like an extra credit or a free month of a certain plan. This is especially convenient if you’re ready for a new carrier but don’t want to give up a like-new iPhone or Samsung Galaxy.

You can typically switch carriers by removing your existing SIM card and inserting a SIM card obtained from your new carrier. Just be sure to check that you can use your device with the new provider’s network. To check if your device is compatible, visit the carrier’s website and look for information on bringing your device or swapping SIM cards.

Who has the best deal?

Every cellphone carrier offers some sort of bundled or family plan. To find the one that’s right for you, focus on the amount of data the packages offer, the monthly charge for each additional line (these will vary), and any additional fees you may incur if you decide to switch to a different plan.

A recent survey by Wirecutter, the New York Times product review website, found the best value as belonging to Consumer Cellular. Their monthly per-line charge is a low $15, with no fees for changing plans. Wirecutter highlighted these Consumer Plans as top deals:

  • A two-line plan, including unlimited talk and 10GB of shared data for $65 a month, was found to be “the best plan for couples.”
  • A four-line plan, with unlimited talk and 20GB of shared data for $105 a month, was selected as “the best plan for a family of four.”

If there is more than one person in your household, you really ought to be in a family cellphone plan. You’ll save money over going it alone. Start by deciding on the data you’ll need, then choose a customized plan that’s just right for your needs and your budget.


5 tips to protect your connected devices and electronic identity

2019-08-16T08:01:01

(BPT) – Resourceful thieves and cyber criminals continue to find new ways to hack U.S. consumers’ sensitive personal information. Dumpster diving, stolen or lost wallets and mail fraud should still be concerns, but the digital age of tablets, smartphones, PCs and Wi-Fi networks leaves people even more vulnerable than ever.

Think about it: Have you ever stored credit card information on your phone for added convenience to make payments in a checkout lane? Do you ever store passwords in apps to transfer funds between accounts? And what’s to keep hackers from accessing a wireless network you check your email on while you’re grabbing a quick cup of coffee?

”More than 15.4 million people a year will experience identity theft, with an average loss of more than $1,000,” said Jane Li, Mercury Insurance’s director of product management. “When one access point closes due to added levels of security, cyber attackers find another. Insurance companies like Mercury provide services that allow homeowners and renters to enjoy the convenience of accessing their connected devices at home and on-the-go, while also helping to protect customers from the potentially devastating effects of criminal infiltration, cyber extortion and identity theft.”

Keeping aware of the latest schemes and ensuring members of your household, friends and others you care about have the right tools helps stop criminals in their tracks.

Following are five do’s and don’ts to help protect your connected devices, as well as your electronic identity, from hackers.

  1. Do power down your devices. This disables the internet connection, cutting off access to any personal information stored on your computer, tablet or phone. Unattended machines, especially if you’re asleep or you leave them at home while on vacation, are easy targets for hackers.
  2. Don’t connect to unsecured wireless networks. Information accessed on an open network, including email passwords and sensitive bank information, is fair game for hackers. Don’t make their jobs easier. Turn off Wi-Fi access on your devices unless it’s a password-protected network you trust.
  3. Do monitor your children’s device usage. It’s a good idea to limit use of computers, tablets and phones to public areas within the home like the living room or kitchen. This makes it easier for parents to keep an eye on who their kids are communicating with, especially on social media or gaming sites, to help prevent the sharing of sensitive information like full names, addresses or other things that can be used for identity theft or other potentially dangerous activities.
  4. Don’t discard important paperwork without shredding it. If it has your name and address, it presents an opportunity for thieves to take advantage and open an account using your information. Remember to shred expired insurance documents, vehicle registrations, bills, loan pre-qualifications and other paperwork that would allow someone to call in pretending to be you. Check your credit reports at least twice a year to ensure all accounts opened in your name are valid.
  5. Do install recommended updates. Smartphone, computer, tablet and smart TV manufacturers, among other providers of connected devices, offer periodic software updates to protect against potential security breaches. Chances are, if an update is recommended, hackers have already discovered a way to access your personal property and information, so keep your software up-to-date.

Li recommends homeowners and renters speak with their local insurance agent to learn more about the endorsements they may be able to add to existing policies to help safeguard their finances if their identities are compromised or connected devices are attacked.

“It can be daunting to try to regain your financial footing if a criminal takes advantage of you,” said Li. “Insurance exists to help protect consumers from unexpected events and, in this case, it’s better to be safe than sorry.”


Time to think harder about your checking account

2019-08-15T07:01:00

(BPT) – When we imagine “financial literacy,” we often think about credit cards, loans and debt. But these building blocks of our financial infrastructures tend to cloud our perspective, pushing important details, like checking accounts, to the sidelines.

Checking accounts are often overlooked but are actually the backbone of personal finance and money management. Routinely using a well-kept checking account allows people to responsibly spend their money. For many, checking accounts are often children, teens and young adults’ first financial accounts, and serve as an introduction to money management and responsible spending.

Because checking accounts are so important, it’s critical that individuals find options that work with their lifestyle and are accessible anywhere. To make the most of your money, here’s what you should look for in a checking account:

1. Read the small print and avoid fees

Opening a checking account feels like a fairly standard practice, so it’s tempting to overlook the fine print. But that’s where hidden fees and charges often linger. The onus is generally on consumers to assess which options work best for them. When reading the fine print, focus on how much — and how often — charges will arise. If a financial institution claims to charge no fee on an account, confirm that there aren’t hidden fees that kick in after a certain amount of time. You don’t want to be surprised later on.

“Look for accounts that are ‘fee-free’ or boast ‘no monthly fees’ so that you ensure your money stays yours,” says Katie Miller, senior vice president of savings products at Navy Federal Credit Union. “It’s worth the time on the front end to save money on needless expenses in the long run.”

2. Access cash anywhere

Take a look at a checking account with a financial institution whose ATMs are scattered around your work, grocery stores and other favorite places that you frequent often. Many checking accounts offer solutions that make your cash even more accessible like ATM fee rebates. Sometimes, your bank of choice will charge you a fee to use an unaffiliated ATM; other times, the ATM itself will charge you a fee to access your money. Rather than pay extra to extract your own cash, some accounts allow you to use any ATM, fee-free. Offers like Navy Federal Credit Union’s Free eChecking account pay up to $120 a year in ATM fee rebates. Use any ATM, anywhere, regardless of fees, and receive up to $10 per statement period to cover those expenses.

3. Accomplish your goals with ease

Free eChecking is a great option for people who are always on the go. Being able to access your money with a few touches of your smartphone makes it easy to budget, plan and manage your money.

“You should bank the way you live,” continues Miller. “Look for offers that allow you to transfer money between accounts, for when you file away a percentage of your paycheck into your savings account. Select a checking account that takes the work out of managing your budget.”

4. Make your money work for you

Find an account that earns you monthly dividends to reward your loyalty and use. “Choosing a checking account that allows your money to earn dividends lets you make money without thinking about it,” says Miller. Some accounts even offer built-in money management tools that let you look at your spending to inform future budgeting endeavors.

Checking accounts teach us the basics of money management: They show us how much money we have and how much we’ve spent in real time. With the right checking account, you can take ownership over your money in a way that can be both impactful and instructive. And when one has the proper insights to avoid unnecessary fees and obstacles, this tool can be the perfect foundation for a healthy financial path.


How to discuss money with your date

2019-07-31T07:01:00

(BPT) – Should you ask someone their credit score on a date? There’s actually an online dating app that’s based on one’s credit score. Maybe it’s not a bad idea.

Apparently, members of the millennial and Gen Z generations agree. With student loan debt at an all-time high, it’s understandable that young adults are more willing to discuss finances than previous generations — even on the first date.

According to a Bankrate survey, millennials are nearly twice as likely to feel comfortable discussing money with a romantic partner — even sharing credit scores and exchanging stories about debt.

Young adults today are coping with the largest burden of student debt of any generation, plus stagnant wages and often limited support from parents who may have been hit hard by the recession. It’s no wonder money is on their mind — and an important consideration when choosing a partner.

If you’re a millennial or Gen Z, what do you need to know about finances? Here are ways to determine if the person you’re dating has a responsible attitude when it comes to debt, credit and finances.

Are they a responsible borrower?

When discussing where you went to school, it’s very common to bring up the subject of student loans and how you’re coping with debt. As they say, misery loves company. You each can share tips and resources that have worked for you. Create a bonding moment out of something you both may be struggling with and learn a few tricks along the way.

Are they living within their means?

One way to cope with debt is to make sure you’re not taking on more. Perhaps after you’ve dated a little while, you may feel safe to bring this topic up. This is something you may be able to subtly pick up in conversations along the way. This is a two-way street, so you must be open sharing your saving plan, goals and debt situation. Being the first person to share can help your partner feel more at ease.

Do they know and understand their credit score?

Your credit score reveals how potential lenders see you. Did you know that traditional credit score models don’t take into account the fact that millennials and Gen Z may have higher assets and income, but are reluctant to take on more debt due to their student loan burden, and so may reflect less credit history? A story in USA Today reported this last year.

A fun tip to share with your date: the VantageScore model assesses younger borrowers more fairly. Over 2.5 billion VantageScore credit scores were provided directly to consumers last year, and you — and your date — can get your free credit score at yourvantagescore.com/free.

Do they think about the future?

Your date may be surprised when you ask how they imagine their retirement, but this can be a great indicator of their financial mindset. If your date sports a flashy wardrobe but gives no thought to the future — or assumes they’ll be wealthy enough to retire at 50 with no current plan — they may not be thinking it through. See if they have similar retirement goals and outlook as you. Keep the conversation light and breezy. You’re just getting to know each other and it’s OK if they have a different financial mindset than you. You can only control your own actions.

Knowing how someone handles their finances can be an indicator of their maturity level and their character. Do they take responsibility for their obligations, or are they just winging it? How far you decide to commit to the relationship may largely depend on what you discover about their attitudes toward money. Understanding your debt situation is the first step toward planning for the future. For more information and helpful tips, check out the VantageScore podcast at vss.credit/itunes.